Key stats
Source: Yahoo Finance. Data as of 03/10/25.
About Cameco Corp
Cameco Corporation provides uranium for the generation of electricity. It operates through three segments: Uranium, Fuel Services, and Westinghouse. The Uranium segment engages in the exploration for, mining, milling, purchase, and sale of uranium concentrate. The Fuel Services segment is involved in the refining, conversion, and fabrication of uranium concentrate, as well as purchase and sale of conversion services. The Westinghouse segment operates as a nuclear reactor technology original equipment manufacturer and a provider of products and services to commercial utilities and government agencies. It also provides outage and maintenance, engineering support, instrumentation and control equipment, and plant modification services, as well as components and parts to nuclear reactors. The company sells its uranium and fuel products and services to nuclear utilities in the Americas, Europe, and Asia. Cameco Corporation was incorporated in 1987 and is based in Saskatoon, Canada.
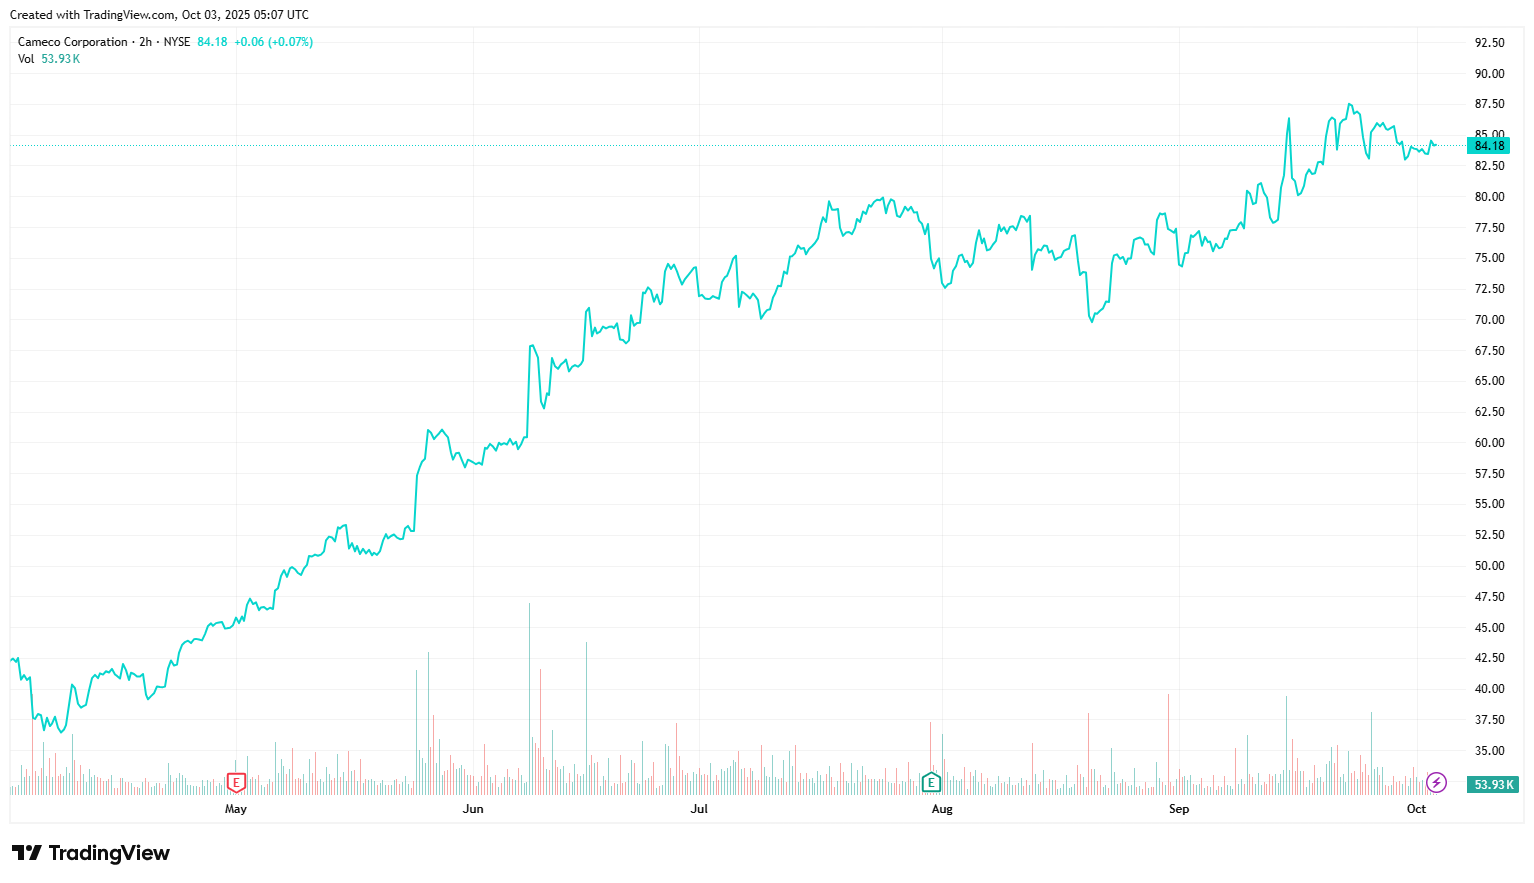
Price Performance
Growth Potential
- Structural uranium supply-demand imbalance from demand tailwinds global nuclear power capacity is growing as countries pursue energy security and decarbonization with >60 reactors under construction worldwide led by China, India, Middle East and dozens of lifetime extensions in the U.S. and Europe) and supply constraints (years of underinvestment during the uranium bear market of 2011-2020 have left global supply short while current uranium prices are not enough to incentivize producers/miners to develop more uranium resources into reserves).
- Strategic vertical integration via Westinghouse expands the company’s role across the nuclear fuel cycle while diversifying revenues beyond cyclical uranium mining.
- Geopolitical tailwinds as western utilities are actively diversifying away from Russian nuclear fuel supply which has increased the premium for politically stable producers like CCJ (low-cost Tier-1 asset base in safe jurisdictions).
- Long-term contracting (~90% total sold under long-term contracts and 10% sold on spot) provides pricing leverage (avoids excessive spot market exposure with contract book being reset at much higher uranium prices than the last cycle) and ensures revenue visibility while capturing upside as prices rise (contracts have a ratio of 40% fixed-pricing and 60% market-related pricing mechanisms).
Key Risks
- Volatility in uranium prices due to cyclical nature of demand (spot and contract prices can swing dramatically with reactor shutdowns, inventory builds or shifts in sentiment with nuclear reactors maintaining strategic fuel inventory, with a single reload allowing 36-months of operation without additional deliveries).
- Operational (mine flooding, restarts, cost inflation) and execution (Westinghouse integration) risks.
- Regulatory (shifts in nuclear policy/reactor shutdowns/anti-nuclear sentiment) and political risks especially in Canada and Kazakhstan.
- Competition from Kazatomprom and state-backed producers.
Frequently asked questions
This article is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy or sell any security. Past performance is not a reliable indicator of future performance. Consider seeking financial, legal and taxation advice before investing.