Key stats
Source: Yahoo Finance. Data as of 15/08/25.
About Cogstate Ltd
Cogstate Limited, a neuroscience technology company, engages in the creation, validation, and commercialization of digital brain health assessments used in both academic and industry sponsored research. Its cognitive services include project management, data management, scientific consulting, statistical analysis, scales procurement, rater training, and monitoring solutions. The company is involved in the design and provision of quality assurance services in clinical trials, focused on the administration, scoring, and recording of conventional brain health assessments. Its technology and associated services are used to quantify the effect of diseases and drugs, and devices or other interventions on human subjects participating in clinical trials primarily conducted by pharmaceutical and biotechnology companies. In addition, the company provides Cognigram, a computerized test to aid healthcare professionals for cognitive decline. Cogstate Limited was incorporated in 1999 and is based in Melbourne, Australia.
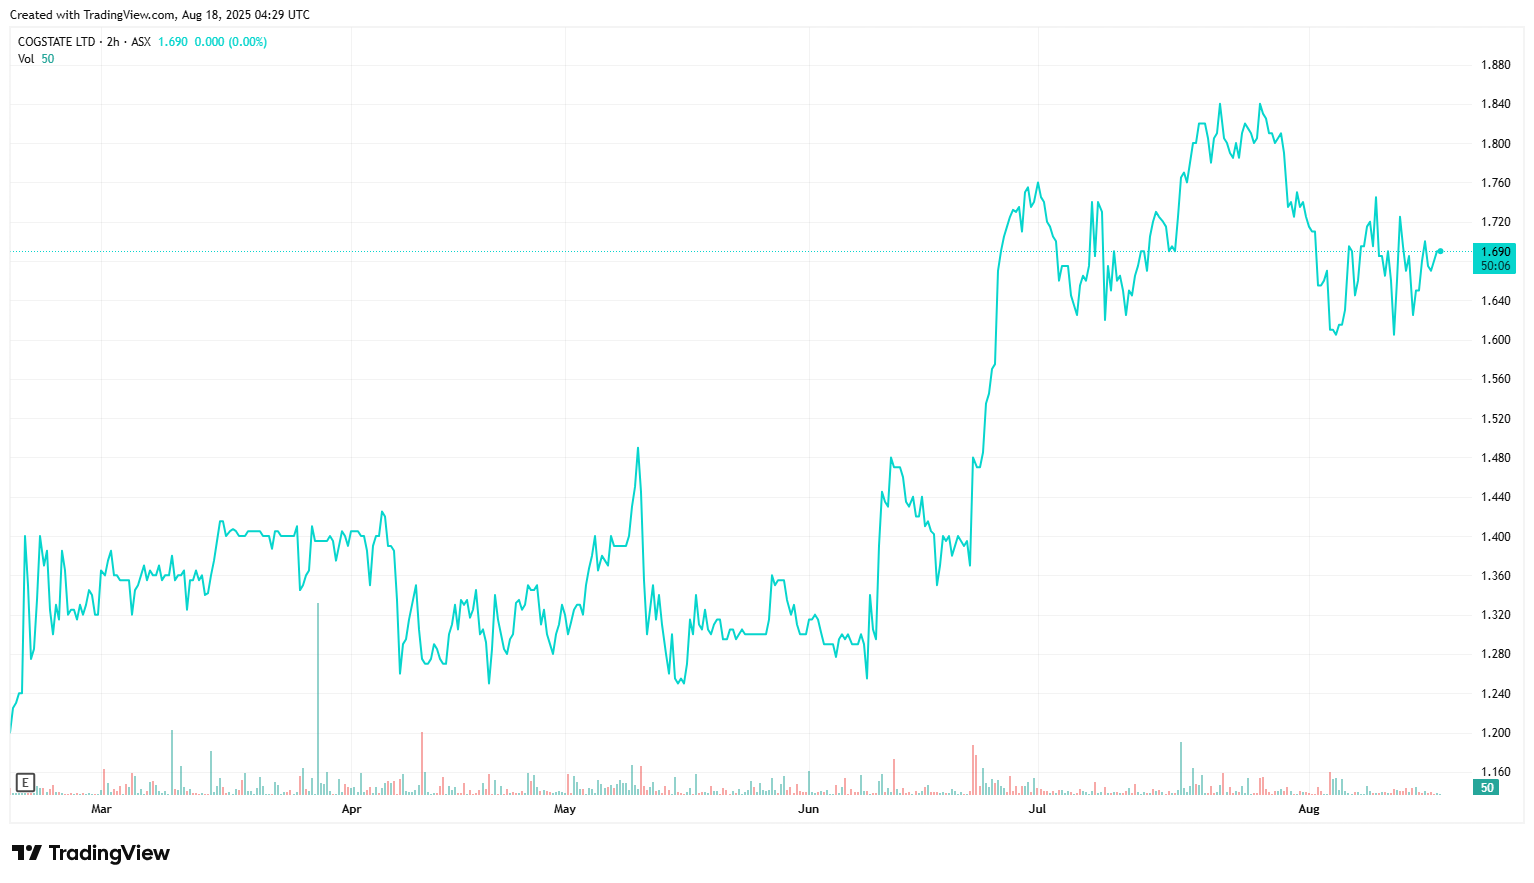
Price Performance
Growth Potential
- Large and Growing Market. Cogstate operates within the global cognitive assessment and training market, which is projected to grow at a 26.2% CAGR through 2033.
- Established Clinical Trials Business. Cogstate's Clinical Trials segment is the company’s cornerstone, contributing over 90% of total revenue. The business is highly entrenched in the pharmaceutical industry, participating in more than 2,400 trials across 100 countries.
- Strategic Partnerships with Pharma Leaders. Key partnerships with pharmaceutical giants like Eli Lilly and Eisai Co. significantly strengthen Cogstate’s commercial position.
- Resilient Business Model. The company’s contracted future revenue backlog of over US$100m provides strong visibility into future earnings.
- Solid financial position. Net cash on the balance sheet and history of profitability with attractive gross & EBIT margins.
- Strong shareholder registry.
Key Risks
- Customer concentration risk.
- Competitive pressures.
- Loss of key customer contracts or management fails to meet their own guidance.
- Lack of liquidity in shares traded given shares are tightly held by long-term investors.
- Regulatory / litigation risks.
Frequently asked questions
This article is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy or sell any security. Past performance is not a reliable indicator of future performance. Consider seeking financial, legal and taxation advice before investing.