Key stats
Source: Yahoo Finance. Data as of 16/09/25.
About EQT Corp
EQT Corporation engages in the production, gathering, and transmission of natural gas. The company sells natural gas and natural gas liquids to marketers, utilities, and industrial customers located in the Appalachian Basin. It also provides marketing services and contractual pipeline capacity management services, as well as involved in risk management and hedging activities. The company was formerly known as Equitable Resources Inc. and changed its name to EQT Corporation in February 2009. EQT Corporation was founded in 1888 and is headquartered in Pittsburgh, Pennsylvania.s.
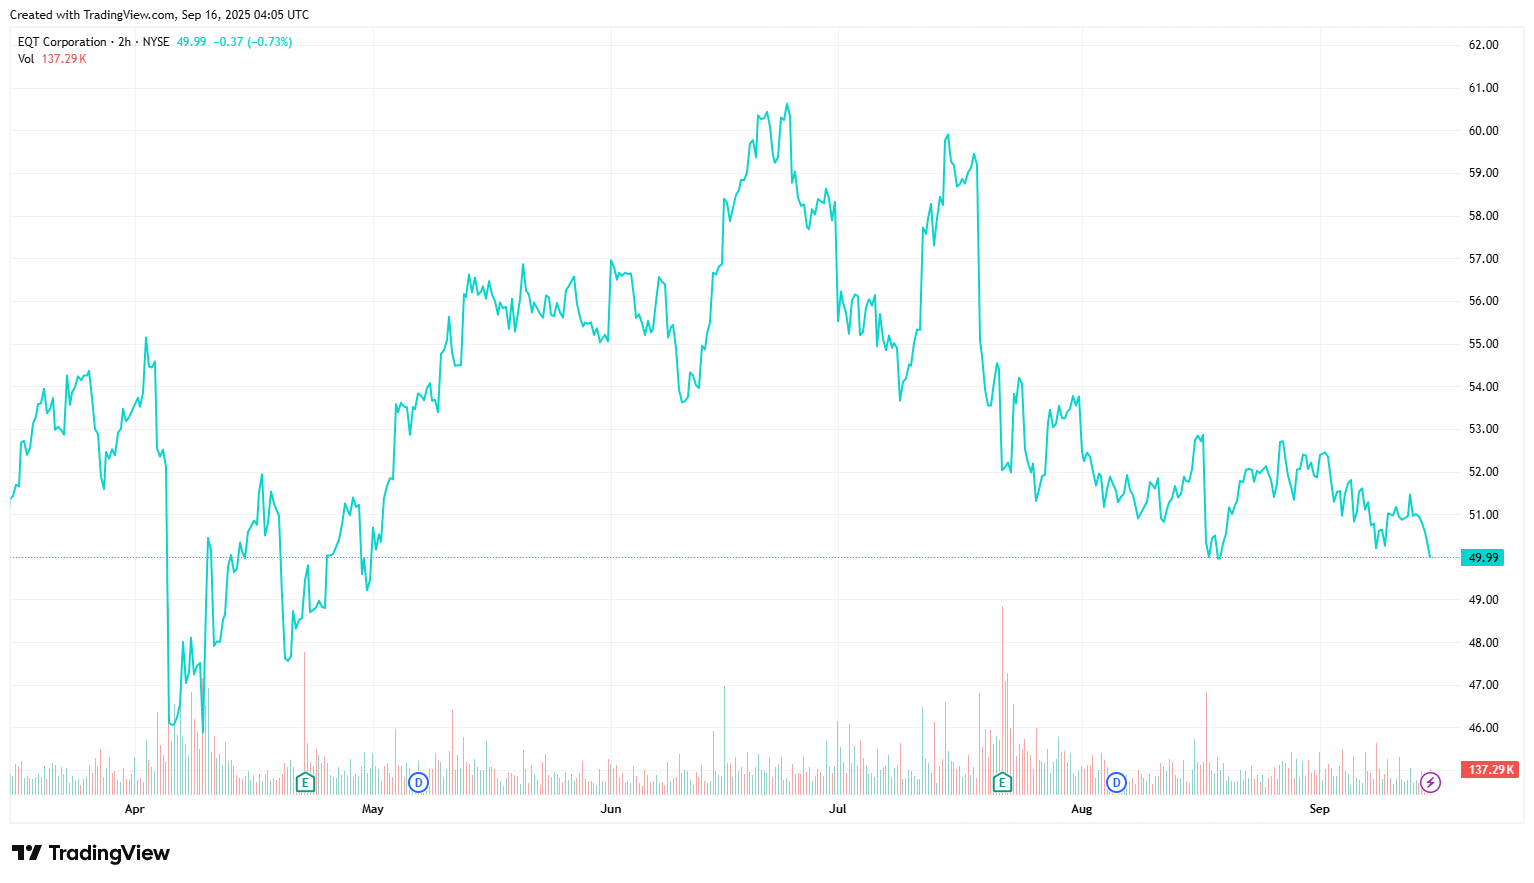
Price Performance
Growth Potential
- One of the largest U.S. natural gas producer, operating ~6–7 Bcf/d, primarily from the Marcellus and Utica shales, while remaining lowest-cost suppliers in North America (management believes it has 3x the number of “extremely low-cost” drilling locations relative to its closest peers), ensuring resilience in downturns and superior margins in price upcycles.
- Strong balance sheet with ongoing deleveraging (targeting ~1x Net Debt/EBITDA vs 3.13x as of FY24) provides financial flexibility to weather gas-price cycles and pursue accretive M&A while increasing buybacks to support price during volatile market.
- Robust FCF profile (generated ~2x FCF vs closest peer in 1Q25).
- Positive LNG market tailwinds with global demand for LNG expected to grow from ~420 mtpa in 2024 to ~650 mtpa by 2030, led by coal-to-gas switching in Asia, energy security concerns in Europe post-Russia war and increased demand for sustainable clean energy (solar/wind provide uncertainty) for datacentres/AI.
- Value accretive M&A (Equitrans deal reduces costs and boosts FCF + Olympus Energy acquisition adds low-cost integrated assets).
Key Risks
- Any oversupply in the market (meaningful supply expected in 2026-28) could see sustained low natural gas prices, compressing margins and FCF.
- Though the company has signed firm transport deals to the Gulf Coast, regulatory/permitting challenges for Appalachian pipelines could lead to basis differential risk (Appalachian producers often sell gas at a discount to Henry Hub due to pipeline constraints).
- Significant change at the senior management level (divisional CEOs).
Frequently asked questions
This article is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy or sell any security. Past performance is not a reliable indicator of future performance. Consider seeking financial, legal and taxation advice before investing.