Key stats
Source: EODHD. Data as of 20/02/26.
About Ferrari NV
Ferrari N.V., through its subsidiaries, engages in design, engineering, production, and sale of luxury performance sports cars worldwide. The company offers sports, track, one-off, and road cars, as well as supercars. It also provides spare parts and engines, as well as after sales, repair, maintenance, and restoration services for cars; and licenses its Ferrari brand to various producers and retailers of luxury and lifestyle goods. In addition, the company operates Ferrari museums in Modena and Maranello; Il Cavallino restaurant in Maranello; and theme parks in Abu Dhabi and Spain. Further, it provides direct or indirect finance and leasing services; range of financial and ancillary services; special financing arrangements; and operates franchised and owned Ferrari stores. The company was founded in 1947 and is headquartered in Maranello, Italy.
Source:EODHD
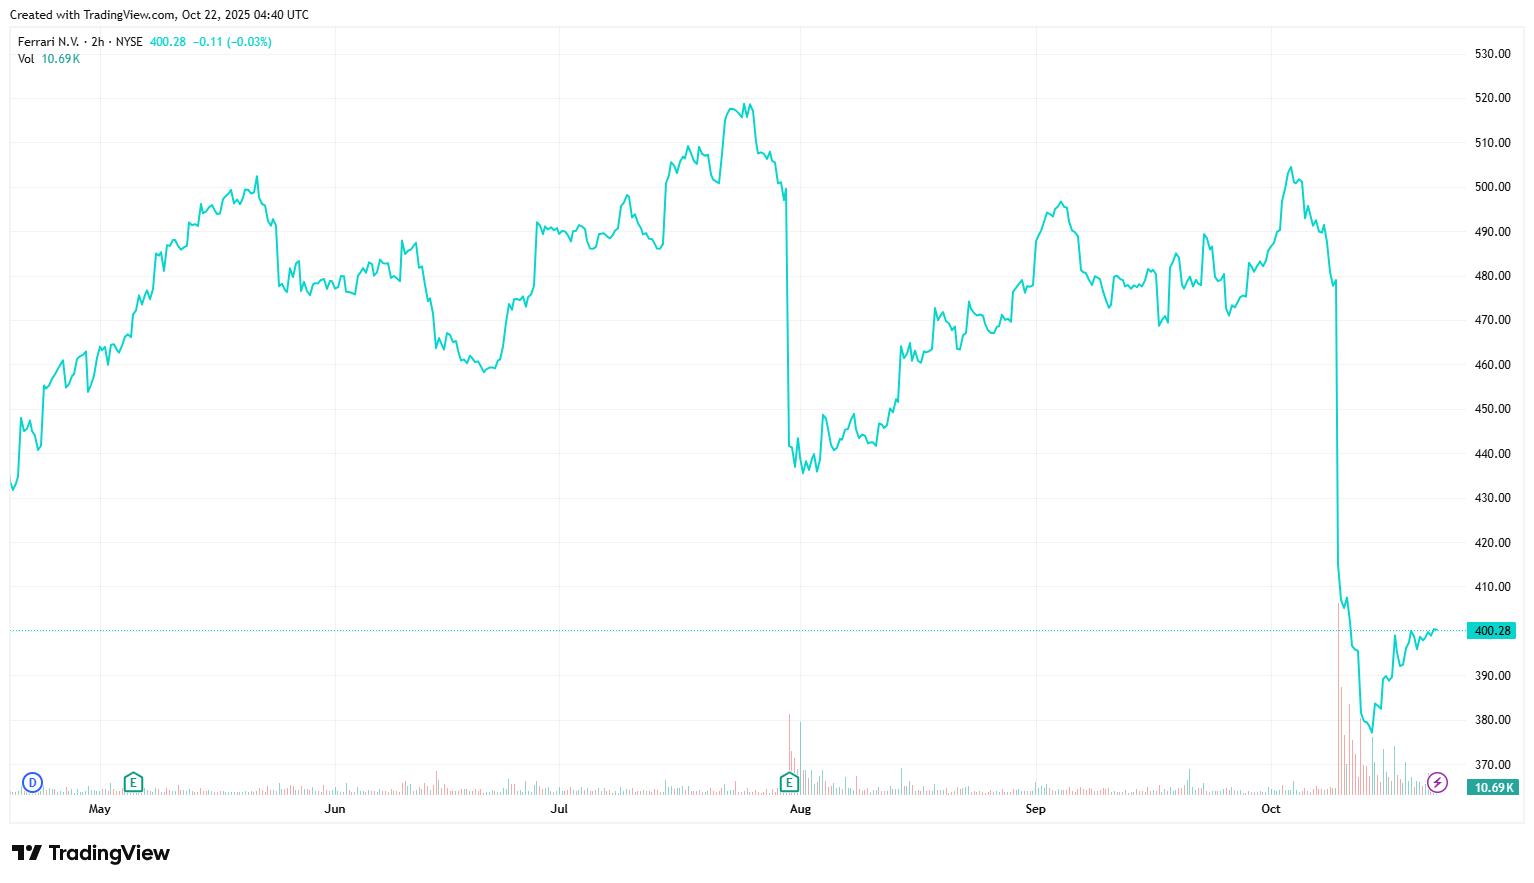
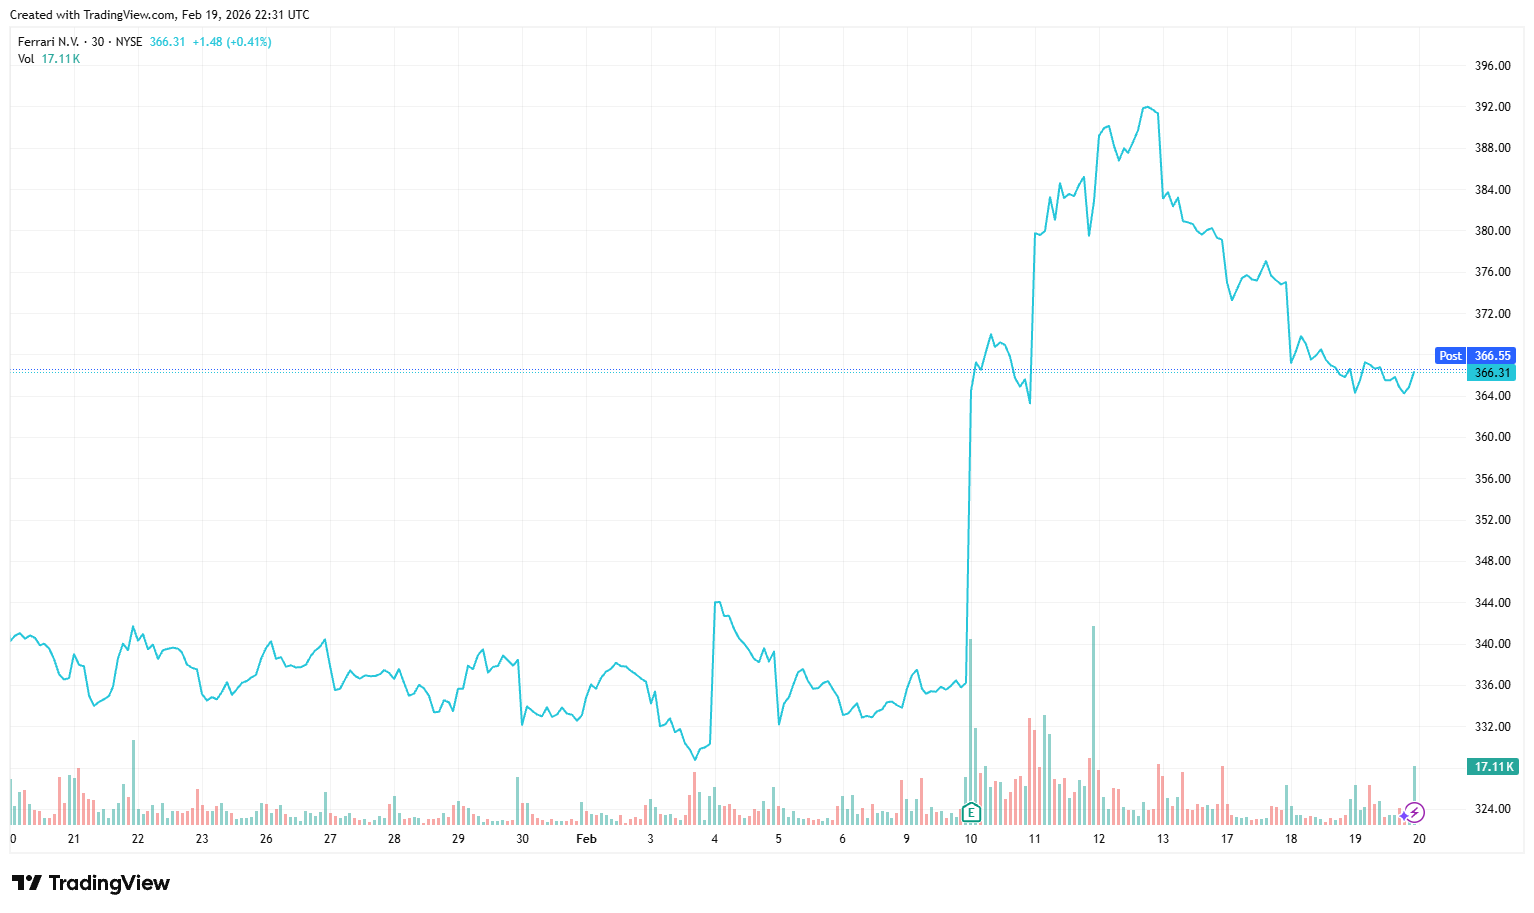
Price Performance
Growth Potential
- Truly an ultra-luxury brand with management focusing on value over growth (i.e. flooding the market with Ferraris). Consequently, RACE enjoys exceptional pricing power, and we would argue limited exposure to economic downturns/affordability.
- Strong track record of growth (since listing has achieved 2x EBITDA growth, +970bps EBITDA margin expansion and ~EUR3bn cumulative industrial FCF).
- Sales momentum driven by new vehicle launches including the move into full electric vehicles. Margin will be driven by price and mix impacts (e.g., personalization).
- Underpenetrated client base opportunity [of ~26 million HNWs, the Company has penetrated ~0.2% to date].
- Strong cash flow generation and solid shareholder returns (expected to deliver ~EUR3.5bn of dividends from 2027-31, with payout increased +500bps to 40% of adjusted net income and buyback authorization increased by EUR3.5bn for 2026-30).
- Strong balance sheet with declining leverage and ample liquidity, which provides the Company flexibility.
Key Risks
- Adverse currency movements, especially EUR strength against the U.S. dollar (USD), Chinese Renminbi (RMB) and Japanese Yen (JPY).
- Increased competition from existing luxury vehicle manufacturers (Lamborghini, Mclaren, Aston Martin) and new emerging brands (Koenigsegg).
- Changes to emissions/fuel efficiency policy which adversely impacts demand.
- Value destructive acquisition of brand(s).
- Less than expected traction for the Company’s upcoming EVs.
- Significant change at the senior management level (divisional CEOs
- Capex blowout in regard to its EV ambitions.
Frequently asked questions
This article is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy or sell any security. Past performance is not a reliable indicator of future performance. Consider seeking financial, legal and taxation advice before investing.