Key stats
Source: Yahoo Finance. Data as of 22/08/25.
About James Hardie Industries Plc
James Hardie Industries plc engages in the manufacture and sale of fiber cement, fiber gypsum, and cement bonded boards in the United States, Australia, Europe, and New Zealand. It operates in three segments: North America Fiber Cement, Asia Pacific Fiber Cement, and Europe Building Products. The company offers fiber cement interior linings, exterior siding products, and related accessories. Its fiber cement products are used for a range of external applications, including siding, cladding, trim, soffit, as well as internal applications such as walls, floors, and ceilings. The company also provides fiber gypsum and cement-bonded boards for interior applications, such as dry lining walls, walls in timber frame buildings, and flooring solutions. Its cement-bonded boards are used in exterior and industrial applications, as well as for fire protection. The company offers its products under the HardieTM brand, such as Hardie Plank, Hardie Panel, Hardie Trim, Hardie Backer, Hardie Artisan Siding, and HardieTM Architectural Collection brands, as well as the fermacell and AESTUVER brands. James Hardie Industries plc was founded in 1888 and is headquartered in Dublin, Ireland.
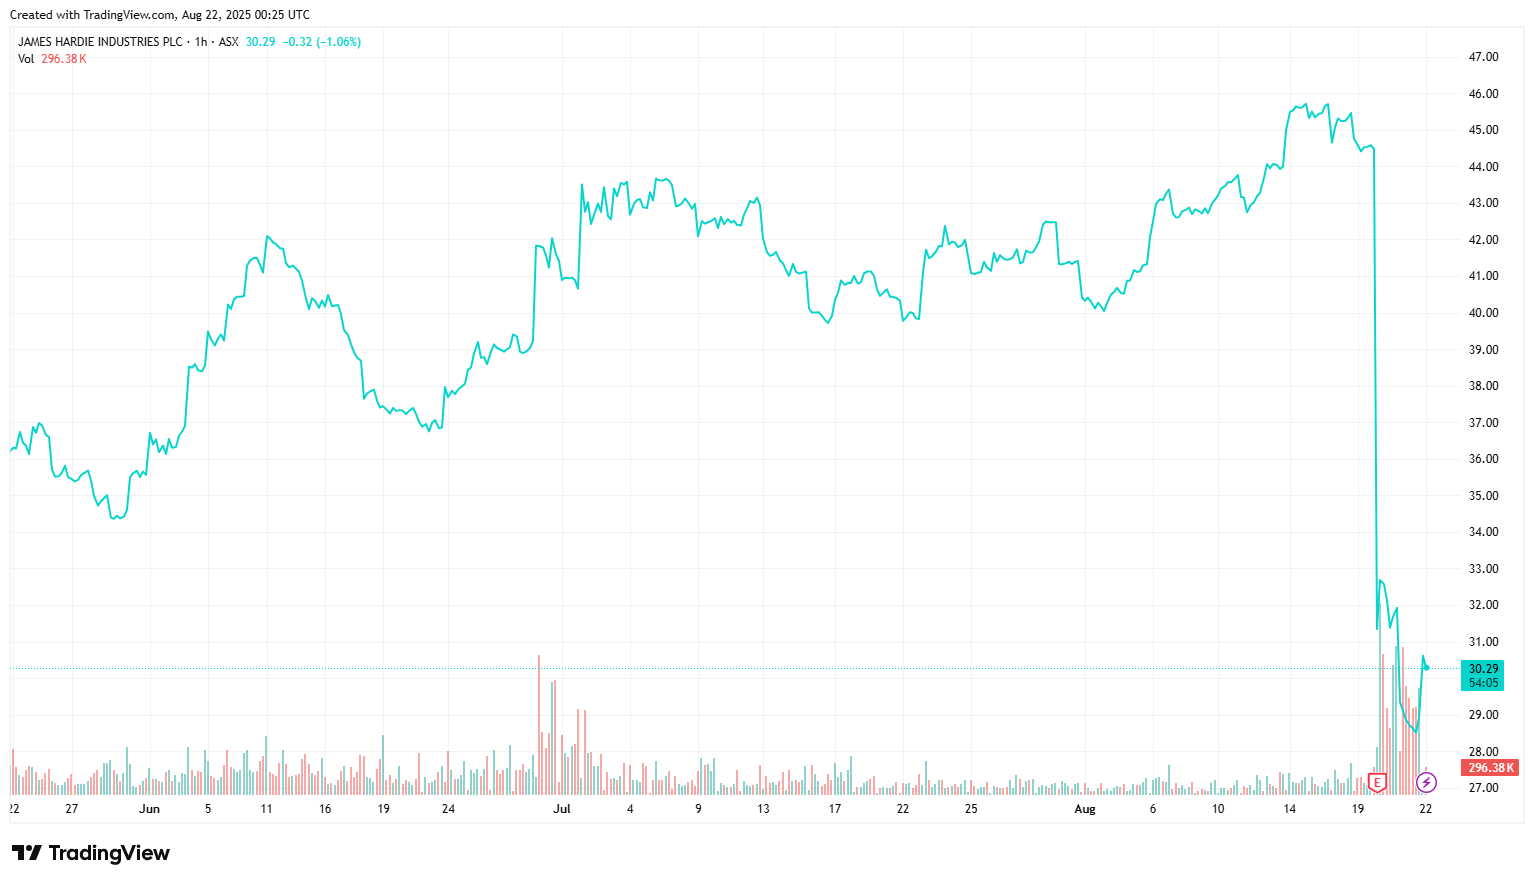
Price Performance
Growth Potential
- Improving momentum in single family new construction homes and potential turnaround in R&R market.
- Fiber cement taking market share from vinyl and other siding products.
- Strong R&D program to stay ahead of competition and product innovation.
- Competent management team with track record of delivering growth (over the past 5-years North American business has grown the top line at a +10% CAGR and expanded adjusted EBITDA margin by more than +400bps).
- Strong long-term aspirations for North America Fiber Cement, namely, to grow revenue double-digits, expand EBITDA margins by another +500bps and triple EBITDA.
- Strong cashflow generation translates to increased shareholder returns (after completion of AZEK) especially given guidance of investments in capacity expansion projects declining for the next few years as recent major projects have reached completion.
Key Risks
- Competitive pressures leading to margin decline.
- Input cost pressures which the company is unable to pass on to customers.
- Deterioration in housing starts (U.S., Australia), significant decline in house prices or deep recession.
- Unable to achieve its growth and market share target, which likely see a de-rating of the stock.
- Adverse movements in asbestos claims.
- Disappointing primary demand growth (PDG) relative to market expectations.
- Manufacturing / operational issues impacting earnings.
Frequently asked questions
This article is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy or sell any security. Past performance is not a reliable indicator of future performance. Consider seeking financial, legal and taxation advice before investing.