Key stats
Source: EODHD. Data as of 16/07/26.
This week's Stock Spotlight is NYSE-listed Wells Fargo & Company.
About Wells Fargo & Company.
Wells Fargo & Company, a financial services company, provides diversified banking, investment, mortgage, and consumer and commercial finance products and services in the United States and internationally. It operates through four segments: Consumer Banking and Lending; Commercial Banking; Corporate and Investment Banking; and Wealth and Investment Management. The company's financial products and services includes checking and savings accounts, and credit and debit cards, as well as home, auto, personal, and small business lending services. It also provides personalized wealth management, brokerage, financial planning, lending, private banking, trust and fiduciary products and services; and financial solutions to private, family owned and public companies through products and services including banking and credit products across multiple industry sectors and municipalities, secured lending and lease products, and treasury management. In addition, it offers a suite of capital markets, banking, and financial products and services, such as corporate banking, investment banking, treasury management, commercial real estate lending and servicing, equity, and fixed income solutions, as well as sales, trading, and research capabilities services to corporate, commercial real estate, government, and institutional clients. Wells Fargo & Company was founded in 1852 and is headquartered in San Francisco, California.
Source: EODHD
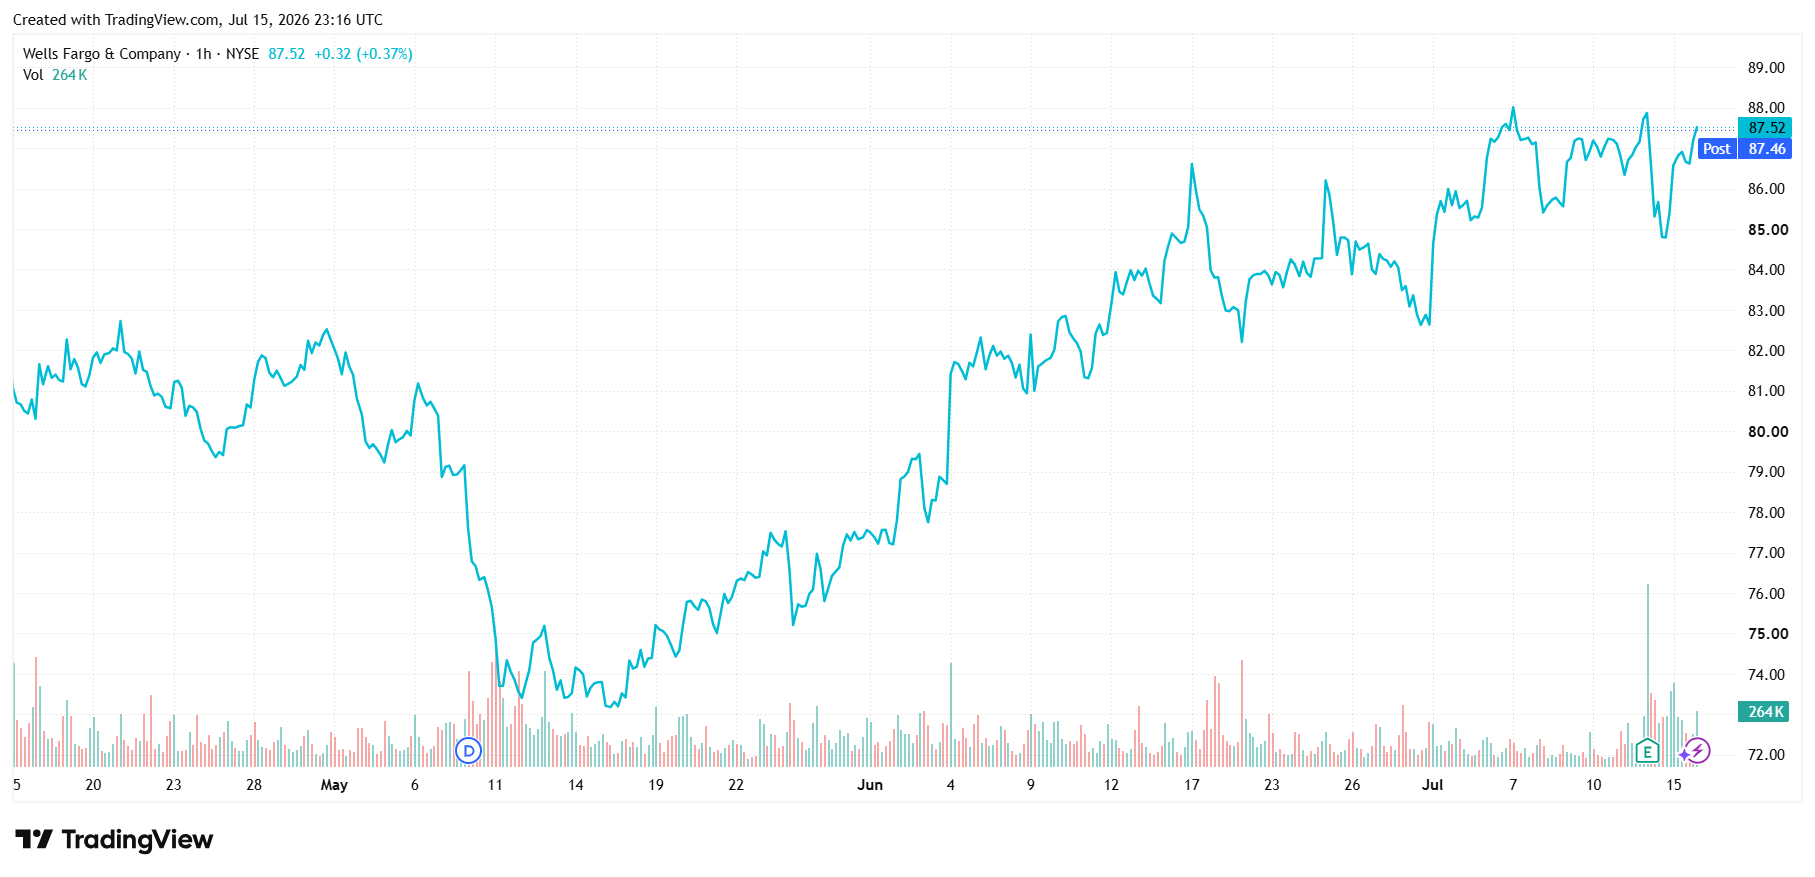
Price Performance
Growth Potential
- Capital returns. 10.3% CET1 ratio supports $7bn in 1H26 buybacks and an expected 11% dividend hike
- Asset cap removal catalyst. Balance sheet unlocked, driving average loans up +12% and deposits up +10% y/y
- CIB market share. Corporate & Investment Banking revenue rose +16% y/y, fueled by record $939m investment banking fees.
- Ongoing focus on efficiency. Headcount cut for 24 consecutive quarters, lowering the efficiency ratio to 60%
- Target profitability. 17.7% 2Q26 ROTCE easily beat legacy goals, prompting a new 17%-18% target.
- Revenue growth broad based. Topline grew 9% y/y to $22.6 Bn, supported by every single operating segment
- Solid asset quality. Net loan charge-off ratio actually improved, dropping 10 bps y/y to 0.34%.
Key Risks
- NIM compression.
- Intense competition for loan growth.
- Funding pressures for deposits and wholesale funding.
- Political and regulatory changes affecting the banking legislation.
- Credit risk with potential default of mortgages, personal and business loans and credit cards.
- CRE exposure
- Consumer acquisition costs with the growing new accounts.
Frequently asked questions
This article is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy or sell any security. Past performance is not a reliable indicator of future performance. Consider seeking financial, legal and taxation advice before investing.