Key stats
Source: EODHD. Data as of 17/06/26.
About WiseTech Global Ltd
WiseTech Global Limited engages in the development and provision of software solutions to the logistics execution industry in the Americas, the Asia Pacific, Europe, the Middle East, and Africa. It develops, sells, and implements software solutions that enable and empower logistics service providers to facilitate the movement and storage of goods and information. The company offers various software solutions for forwarding and customs, landside logistics, digital documents, transport and specialist warehouse management system, carrier and rates, and enterprise. WiseTech Global Limited was incorporated in 1994 and is based in Alexandria, Australia.
Source: EODHD
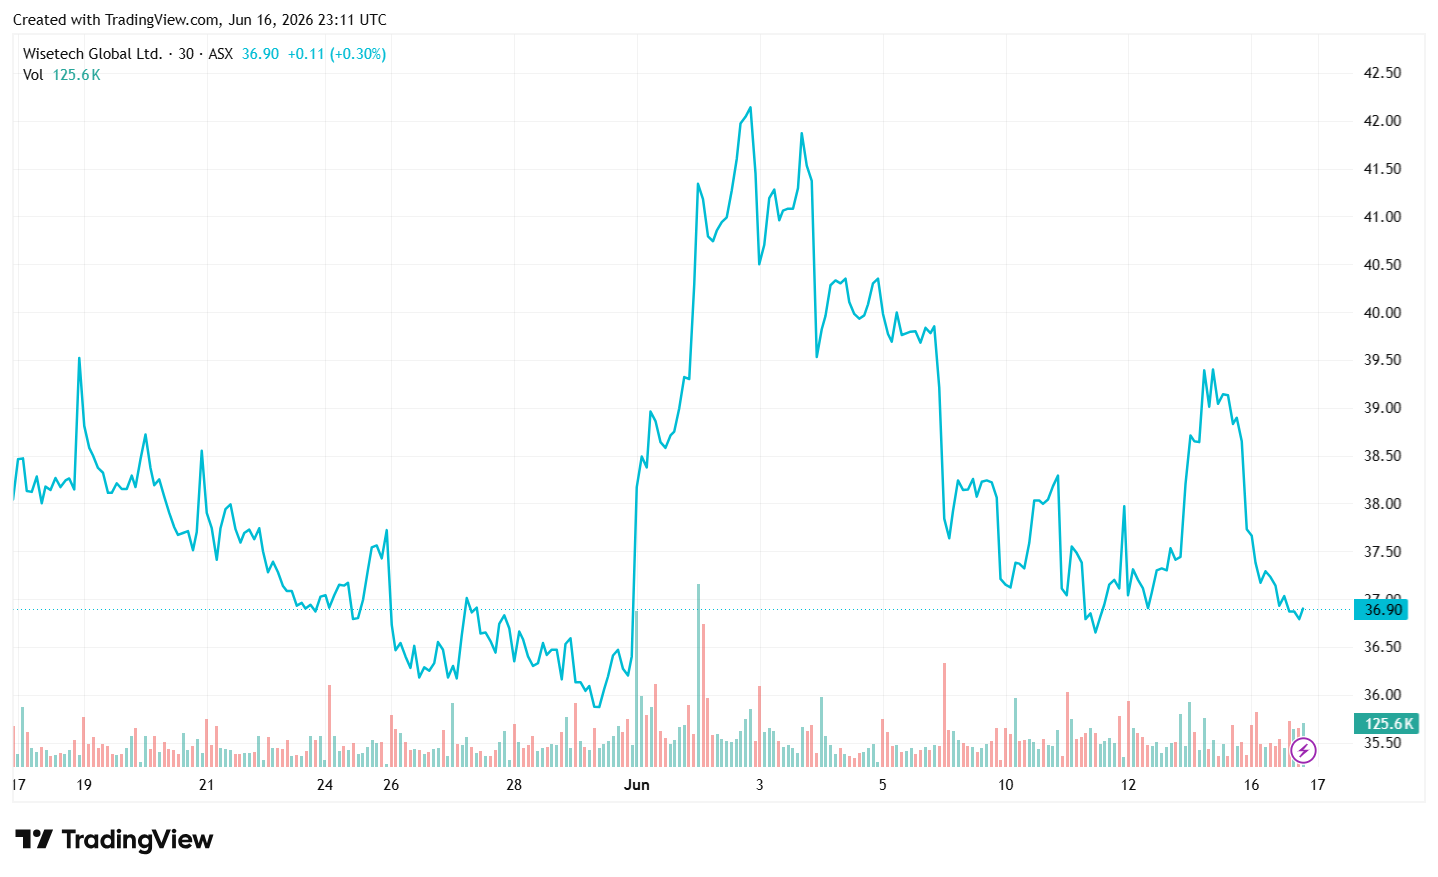
Price Performance
Growth Potential
- Trading below our blended valuation (DCF, PE-multiple, EV/EBITDA multiple).
- The DSV risk could be isolated. Developing an in-house system (even with the advantage of AI models) will likely cost more than $200m and be a multi-year project. Therefore, we argue that only tier 1 forwarders who currently spend more than the build cost annually or have acquired a system (DSV acquired Tango with the Schenker acquisition) would genuinely have this option available to them.
- New product launches could add to future revenue growth and potentially add to WTC’s moat (raising the barriers to entry).
- Ongoing focus on cost efficiency will likely see WTC margins improve, in our view.
- Market leading position (significantly ahead of the nearest competitor).
- Geopolitical tensions considered by management as “tailwinds” due to higher consolidation of the logistics software industry.
- Potential M&A target.
Key Risks
- WTC announces another earnings downgrade.
- Emerging competitive threat (new product/technological advancements).
- Corporate governance issues may also result in WTC being sold by investors with a strong focus on ESG.
- Delays to new product launches miss market expectations.
- Organic growth could moderate further, which may no longer warrant such a lofty valuation.
- Disruption to technology (data breach).
Frequently asked questions
This article is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy or sell any security. Past performance is not a reliable indicator of future performance. Consider seeking financial, legal and taxation advice before investing.