
Saudi Arabia’s Stock Market Opens to Global Investors: From Peripheral Market to Strategic Allocation

The move sits squarely within the Kingdom’s Vision 2030 agenda, an ambitious plan to diversify the economy away from oil dependence and towards a more sustainable, private-sector-led growth model. Capital markets play a critical role in this transition, both as a source of funding and as a mechanism for enforcing discipline, transparency, and global integration.
For global investors, Saudi Arabia’s relevance has grown substantially. Tadawul, the Saudi stock exchange, now ranks among the largest equity markets outside the developed world, with a scale that cannot be considered peripheral. Combined with structural reforms, benchmark inclusion, and rising institutional participation, Saudi Arabia is increasingly intersecting with global capital allocation decisions rather than remaining on the margins.
The Evolution of Saudi Arabia’s Capital Markets
Historically, Saudi Arabia’s equity market was largely inward-looking. Tadawul, formerly known as the Saudi Stock Exchange, was established in 2007 and for much of its early history functioned as a predominantly domestic market. Trading activity was driven primarily by local retail investors and domestic institutions, with foreign participation either prohibited or tightly constrained. As a result, the market remained largely insulated from global capital flows, valuation frameworks, and institutional governance expectations.
The gradual evolution of Saudi Arabia’s capital markets began in earnest in 2015, when the Kingdom first allowed limited foreign participation through the introduction of the Qualified Foreign Investor (QFI) regime. This marked a pivotal shift, granting selected international institutions direct access to Saudi equities for the first time, albeit under strict eligibility criteria and ownership limits. While limited in scope, the QFI framework laid the foundation for broader liberalisation and signalled the Kingdom’s intent to integrate more fully with global financial markets.
Over the following decade, reforms accelerated. Trading, clearing, and settlement infrastructure were modernised, and foreign ownership rules were progressively eased. Saudi Arabia’s liberalisation path shares similarities with other emerging market openings, such as China’s phased A-share inclusion and India’s gradual expansion of foreign portfolio investors. However, Saudi Arabia’s approach is distinctive. Unlike smaller frontier markets, the Kingdom is opening one of the largest markets globally by capitalisation, making its reform agenda immediately relevant to international investors.
The Reform Agenda Behind the Move
Capital market reform is central to Vision 2030. The objectives are multi-layered. Broadening market access allows domestic companies to raise capital more efficiently and at competitive costs. The presence of international investors is intended to enhance governance standards, disclosure practices, and market credibility. Deeper markets support privatisation initiatives, providing a platform for initial public offerings and secondary offerings of state-linked assets.
The Capital Market Authority has led reforms to align market infrastructure with international norms, improving settlement cycles, custody arrangements, and disclosure requirements. Governance standards remain uneven, but the overall direction points toward greater convergence with global practices. Benchmark inclusion has been a strategic focus. Integration into major global indices such as MSCI Emerging Markets and FTSE Russell ensures that capital inflows are structurally embedded, rather than solely discretionary, strengthening the market’s credibility and visibility.
What Has Changed: Scope of Foreign Access
The most visible change for investors is the expansion of foreign access beyond the original QFI framework. Simplification of regulatory requirements has lowered barriers to entry, reduced administrative complexity, and expanded the pool of eligible investors. Ownership limits have been relaxed, custody and settlement processes streamlined, and operational frictions reduced, improving investability for large institutional investors.
Saudi Arabia’s inclusion in major benchmarks has reshaped its role in global portfolios. Passive inflows linked to index inclusion have increased liquidity and raised visibility among active managers. The market is no longer reliant solely on episodic foreign interest; it is now structurally integrated into global capital flows. Valuation, volatility, and trading dynamics are increasingly influenced by international factors alongside domestic developments.
Market Overview and Fundamentals
Tadawul ranks among the world's top ten exchanges by market capitalization, with over 200 listed companies spanning USD3 trillion in value, surpassing many developed and emerging peers. The market is heavily weighted towards financials, energy, materials, and telecommunications, reflecting the structure of the Saudi economy.
Saudi Aramco remains the dominant constituent, anchoring the market’s energy exposure, while large banks and industrial companies provide depth and liquidity. Trading volumes have increased significantly in recent years, supported by both domestic retail participation and rising institutional flows.
From a valuation perspective, Saudi equities have often traded at a premium to traditional emerging markets, reflecting their scale, profitability, and relatively strong balance sheets. At the same time, sector concentration and state influence introduce characteristics that differentiate Saudi Arabia from more diversified emerging markets.
Saudi Arabia does not fit neatly into the typical emerging market classification. Its fiscal capacity, currency stability, and geopolitical influence place it in a hybrid category, combining elements of emerging market growth with features more commonly associated with developed markets.
Implications for Investors
For investors, Saudi Arabia’s market opening is a practical portfolio consideration rather than an abstract policy shift. The focus has moved from market access to how exposure can contribute to portfolio outcomes.
Key considerations include:
Scale and inevitability. Saudi Arabia’s market size, liquidity, and growing index weight mean it can no longer be treated as a marginal emerging market allocation. For benchmark-aware investors, under-allocation increasingly reflects an active positioning choice rather than neutrality.
Distinct return profile.
Saudi equities offer differentiated drivers within emerging markets, including strong balance sheets, consistent dividends, and earnings exposure linked to domestic consumption, infrastructure investment, and financial deepening rather than export-led cycles.
Diversification benefits. The market has historically shown lower correlation to developed markets and traditional emerging markets, supported by currency stability and domestically driven growth, offering potential portfolio diversification rather than incremental EM risk.
Selective active opportunity. Despite rising passive inflows, research coverage remains uneven relative to market size. This creates scope for active managers to identify mispricing through fundamental analysis and governance assessment, particularly among large-cap names.
Timing and optionality.
Market liberalisation phases often present structural inefficiencies before ownership and valuation frameworks fully converge with global peers. For long-term investors, phased exposure allows participation while the market continues to mature.
These characteristics suggest Saudi Arabia is evolving from a peripheral emerging market into a strategic allocation consideration. The relevance lies in thoughtfully calibrating exposure within a broader portfolio rather than making a binary entry decision.
Risks and Considerations
Despite progress, risks remain material. Geopolitical dynamics in the Middle East continue to shape investor sentiment, even when domestic fundamentals are strong. Oil price volatility remains a key macro variable, influencing fiscal policy, liquidity, and market confidence.
Corporate governance and transparency standards, while improving, are still uneven across the market. State ownership and influence can complicate minority shareholder considerations, particularly during periods of policy-driven intervention.
The Saudi riyal’s peg to the US dollar provides currency stability but also links monetary conditions closely to US policy. Liquidity, while improving, remains concentrated in a relatively small number of large-cap stocks, which can amplify volatility during periods of stress. Selectivity and active risk management are therefore essential when allocating to Saudi equities.
A Market Moving From Peripheral to Relevant
Saudi Arabia’s capital market liberalisation marks a structural shift in global investing. Tadawul can no longer be dismissed as a niche or inaccessible market. Its scale, reform trajectory and integration into global benchmarks demand attention from global investors.
The opening of the market reflects a broader ambition to embed Saudi Arabia within global capital markets and to use financial reform as a catalyst for economic transformation. For investors, the opportunity lies not in a binary decision to enter or avoid the market, but in understanding how and when to engage as the market continues to evolve.
As with all emerging opportunities, investors should consider how Saudi equities align with broader portfolio goals, balancing scale, risk, and return characteristics. Measured exposure, phased participation, and ongoing monitoring of reforms and governance improvements will be key to capturing the market’s evolving opportunities.
Subscribe to our newsletter
Disclaimer: This article does not constitute financial advice nor a recommendation to invest in the securities listed. The information presented is intended to be of a factual nature only. Past performance is not a reliable indicator of future performance. As always, do your own research and consider seeking financial, legal and taxation advice before investing.
Speak to an Advisor
Inside Anthropic’s IPO filing: explore its soaring revenue, computing commitments, reported losses and governance structure, and what the disclosures mean for investors.
Big Tech reports next week. Learn how to read earnings releases and filings, and what to look for in AI spending, cloud growth, cash flow and guidance.
Understand how AI investment could affect global financial stability, as the IMF and RBA warn of rising debt, market concentration and funding risks.
Firmus’ proposed mega-IPO puts a spotlight on the cost, capital intensity and risks of building AI infrastructure as investors weigh the next phase of the AI boom.
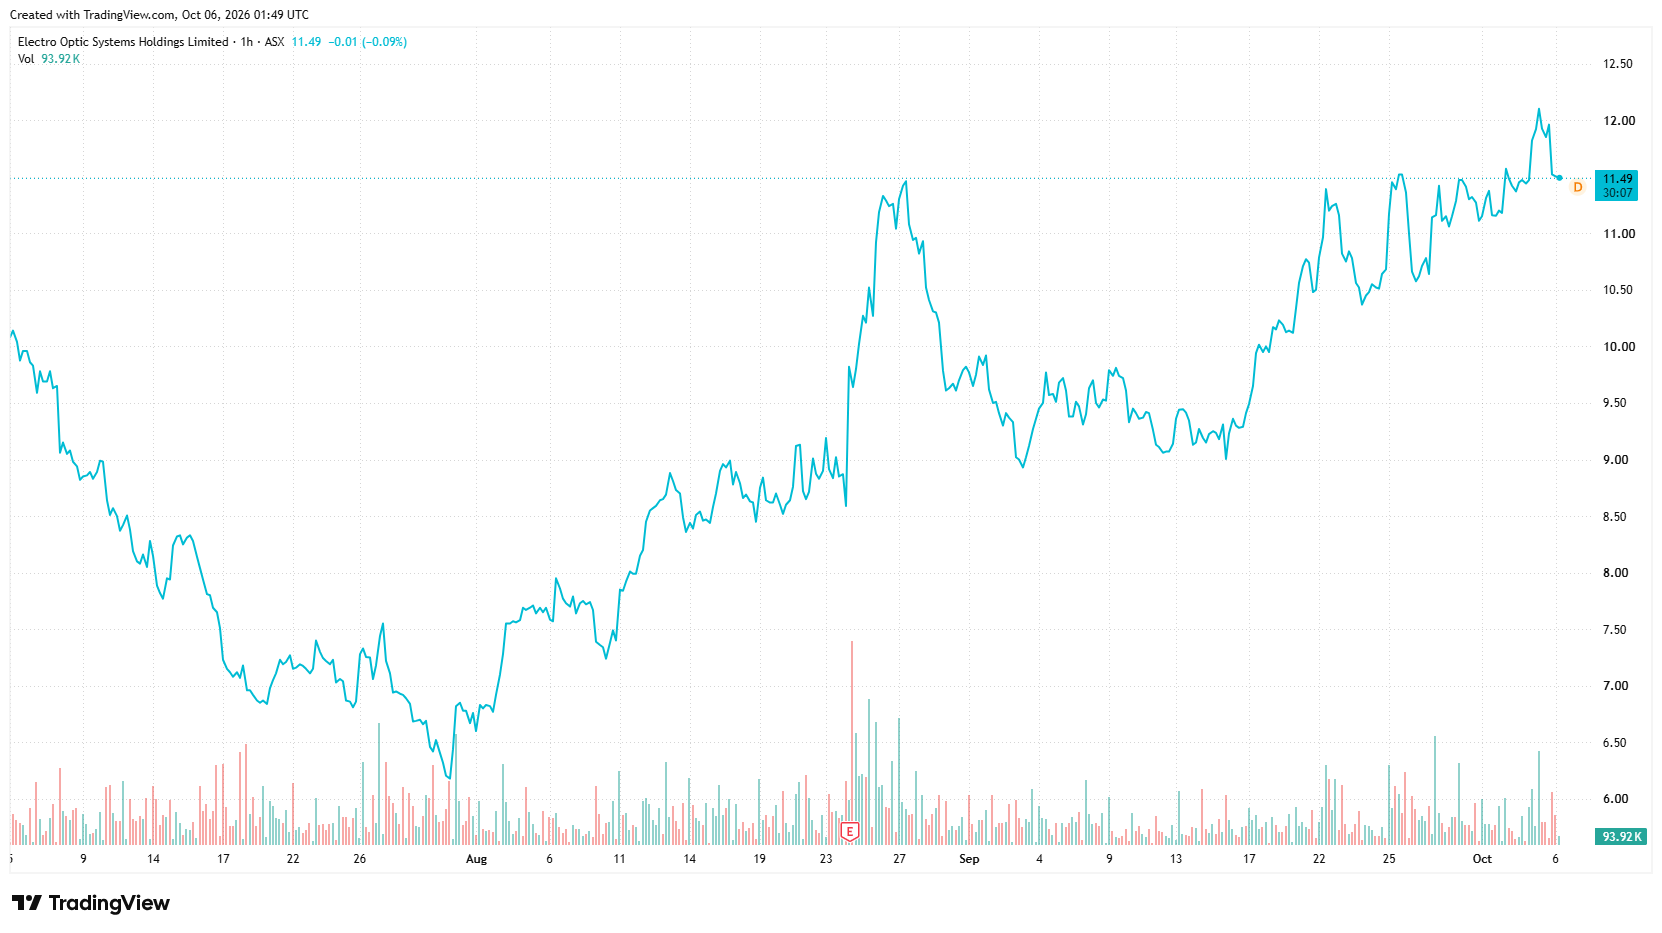
About Electro Optic Systems Holdings Ltd. Electro Optic Systems Holdings Limited engages in the development, manufacture, and sale of telescopes and dome enclosures, laser satellite tracking systems, remote weapon systems, and high laser weapon. It operates through Defense Systems and Space Systems segments. The company develops, manufactures, and markets fire control, surveillance, weapon systems, and high energy laser to military customers. It also provides passive optical and laser sensing equipment; optical, microwave and on-the-move radio and satellite products; and laser-based surveillance systems with space tracking capability. In addition, the company offers counter-drone, firepower, force protection, and UGV and marine lethality systems, as well as high energy laser weapon; optical tracking systems, space control, space domain awareness, satellite laser ranging, space sustainability, and precision optics. It operates in Australia, the United States, Singapore, the United Arab Emirates, the United Kingdom, New Zealand, the Netherlands, North America, Germany, and rest of Europe. Electro Optic Systems Holdings Limited was founded in 1983 and is based in Symonston, Australia. Source: EODHD Key Stats
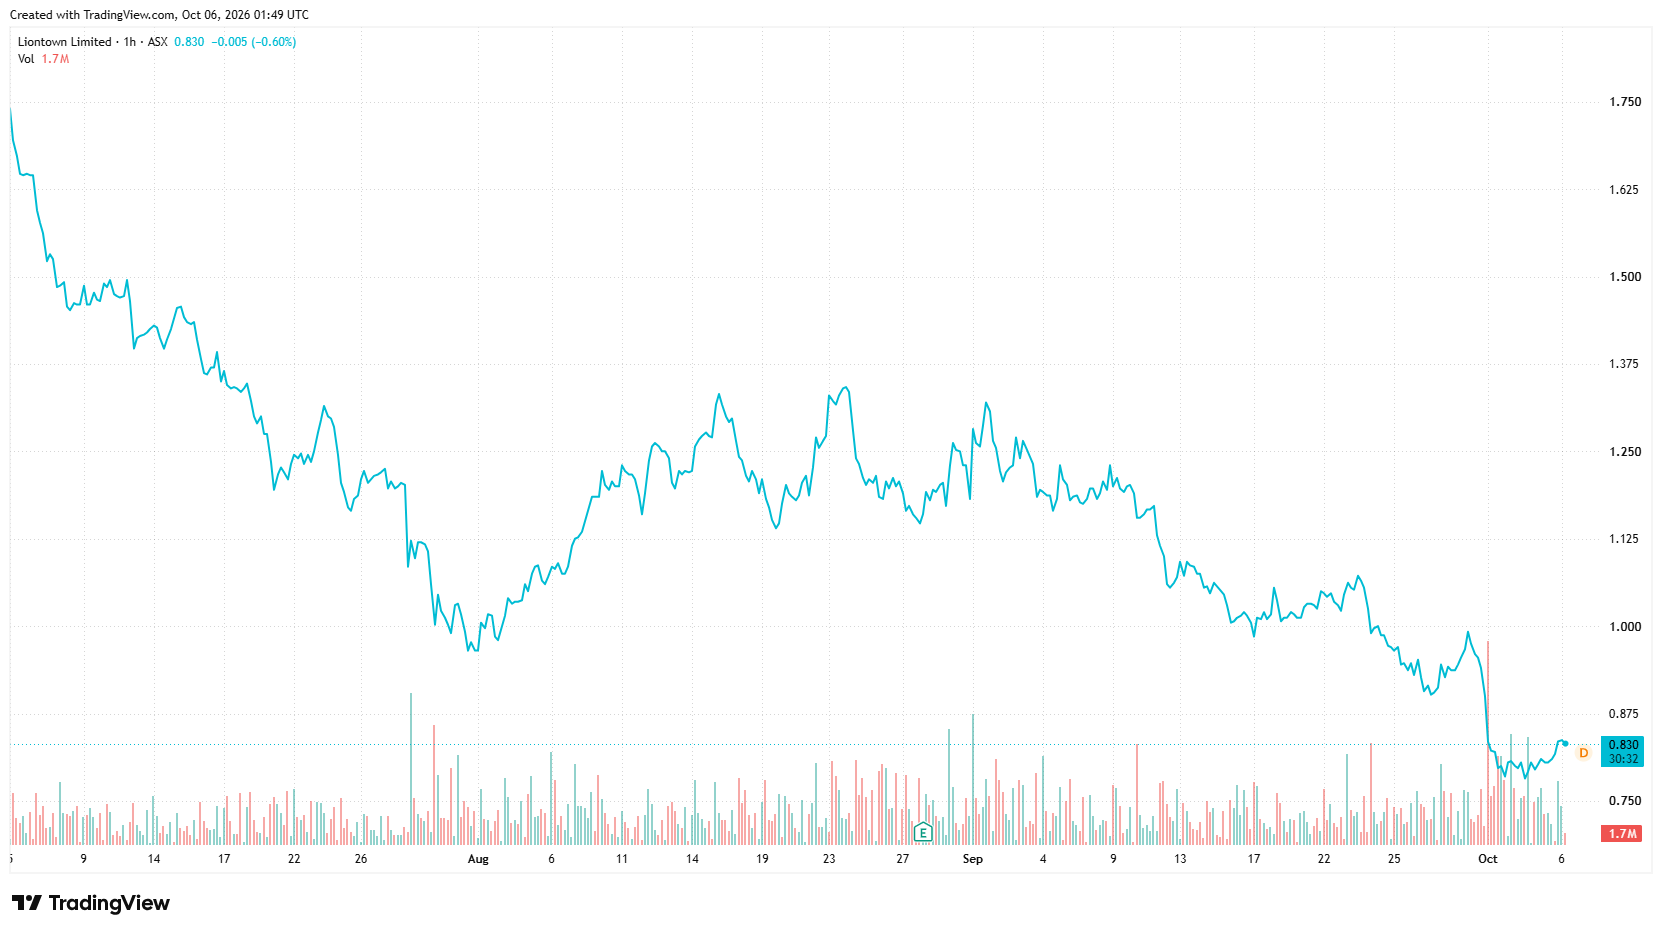
About Liontown Ltd. Liontown Limited engages in the exploration, evaluation, and development of mineral properties in Australia. It primarily explores for lithium, gold, and nickel deposits. The company's flagship property is the Kathleen Valley lithium project located in Perth, Western Australia. The company was formerly known as Liontown Resources Limited and change its name to Liontown Limited in November 2025. Liontown Limited was incorporated in 2006 and is headquartered in West Perth, Australia. Source: EODHD Key Stats
The RBA has raised rates to 4.60% as inflation pressures persist. Explore the impact of energy costs, AI demand and the key signals investors should watch next.
Discover how advances in genomics, AI, diagnostics and gene editing are creating a broader healthcare opportunity and where commercial value is emerging.
The AI trade is being forced to rethink the pace of progress. Here is what investors should watch across Nvidia, chips, AI spending, software and adoption.

Copper is at a record high, yet the global market still has a surplus. So where is all the copper, and why is it becoming harder to find?
