
The Global Supply Chain of War: How China’s Drone Components Are Shaping the Russia-Ukraine Conflict

For investors, this development reflects more than a geopolitical curiosity. It represents a structural shift in how defense technology is sourced, manufactured, and regulated. In an era of heightened great power competition and supply chain nationalism, these dynamics influence market outcomes across equities, commodities, and alternative assets.
The New Face of Modern Warfare
Ukraine’s battlefields have become a testing ground for 21st-century warfare. Unlike traditional tank-dominated conflicts, this war is increasingly fought from the air using unmanned aerial vehicles (UAVs). These range from small commercial drones adapted for reconnaissance to loitering munitions capable of precision strikes.
Deployment scales are significant. Both Russia and Ukraine operate thousands of drones each month, with attrition rates far higher than conventional military aircraft. Ukraine uses consumer-grade quadcopters alongside purpose-built military drones, while Russia relies on Iranian-designed Shahed drones and domestically produced systems.
What makes this especially relevant is the supply chain supporting these operations. Modern drones combine semiconductors from Taiwan, cameras from Japan, batteries from China, and assembly that can occur in multiple locations. This distributed production model, long a source of efficiency in consumer electronics, now underpins battlefield capability, with China emerging as a central node in this ecosystem.
Mapping the Supply Chain: China's Role in Global Defense Components
China occupies a pivotal position in the global drone supply chain, particularly at the component level. While finished drones may be assembled in various jurisdictions, the underlying inputs often originate from Chinese manufacturers, including lithium-ion batteries, electric motors, cameras, sensors, flight controllers, radio-frequency modules, and a range of low- to mid-tier semiconductors.
Many components are dual-use. High-resolution cameras for consumer drones, GPS modules for logistics, and battery management systems for electric vehicles can be repurposed for military applications with minimal adaptation. China’s advantage lies in scale, cost efficiency, and vertically integrated electronics and energy storage manufacturing, rather than direct defense production.
Chinese manufacturers typically supply global distributors rather than military end users, allowing components to flow through layered commercial networks and reach both Russian and Ukrainian forces via intermediaries and third-party jurisdictions. This commercial-to-military pipeline blurs the boundary between civilian industry and defence supply chains, limiting traceability and complicating enforcement. Rather than reflecting deliberate state-level military support, it highlights a structural reality of modern conflict: globalised electronics ecosystems optimised for commercial efficiency now underpin battlefield capability, without the visibility or control mechanisms required to prevent diversion into military applications.
Geopolitical Implications and Risk Assessment
China maintains a stance of neutrality, publicly calling for de-escalation while deepening economic ties with Moscow. Yet the ongoing flow of dual-use components has created tension with the United States and European allies, exposing the gap between official statements and supply-chain realities.
Washington’s concern is less about direct military support and more about indirect enablement. China has avoided providing overt military aid to Russia, a step that would likely trigger severe sanctions. However, the continued availability of commercially sourced components enables Russian drone production and battlefield replenishment. This has created a narrow policy corridor for U.S. authorities, who are attempting to tighten export controls and pressure intermediaries without precipitating a broader rupture in U.S.–China economic relations.
Enforcement remains a core challenge. Unlike traditional weapons systems, electronic components are fungible, widely distributed, and deeply embedded in civilian trade networks. Semiconductors, camera modules, and communication hardware often pass through multiple jurisdictions, making end-use tracking difficult and providing intermediaries with plausible deniability. Each additional node in the supply chain reduces traceability and complicates sanctions enforcement.
These dynamics elevate the risk of secondary sanctions, regulatory spillovers, and abrupt compliance changes across sensitive technology sectors. The drone supply chain has become part of a wider technology decoupling process, alongside semiconductors, artificial intelligence, and advanced manufacturing. This decoupling is unlikely to be comprehensive or linear, but rather characterised by selective restrictions, targeted reshoring incentives, and heightened scrutiny of supply-chain exposure. Markets will increasingly need to price not only direct geopolitical risk, but also the structural fragmentation of global technology ecosystems.
Investment Implications Across Sectors
The supply chain dynamics of modern warfare create differentiated opportunities and risks across multiple sectors and geographies.
Defense and Aerospace: Traditional Western defense contractors such as Lockheed Martin, Northrop Grumman, and Raytheon have benefited from increased NATO budgets. The drone revolution, however, favors more agile players. Companies like AeroVironment and Kratos Defense & Security Solutions offer exposure to unmanned systems without the legacy cost structures of prime contractors. European firms focused on electronic warfare and counter-drone systems also stand to benefit as the continent remilitarizes.
Semiconductor Industry: The conflict has accelerated semiconductor supply chain regionalization. U.S. fabrication expansion by Intel, TSMC’s Arizona facilities, and European Chips Act investments respond directly to vulnerabilities highlighted by Ukraine. Chinese semiconductor firms face restrictions that may limit both market access and technology acquisition, creating a bifurcated market.
Chinese Equities:
Companies involved in dual-use technologies carry elevated risks. While most Chinese electronics manufacturers are not sanctioned, potential designation or broader restrictions create uncertainty. DJI exemplifies this risk, already banned from U.S. government procurement and facing ongoing scrutiny.
Defense Supply Chain Enablers:
Firms providing specialized components such as secure communications systems, advanced composites, and radiation-hardened electronics benefit from increased defense spending. Western suppliers able to guarantee China-free sourcing can command premium valuations for strategic sourcing capabilities.
Critical Materials: Defense production requires specific commodities—titanium for airframes, rare earth elements for electronics, lithium for batteries. The conflict has highlighted concentration risks in these materials, particularly given China's dominant position in rare earth processing. Companies developing Western-hemisphere sources of critical materials present strategic value beyond typical commodity exposure.
Risk Factors for Portfolio Consideration
Despite the opportunities, the risks are substantial. Regulatory and compliance risks remain elevated, particularly for companies with complex international supply chains. Sudden policy shifts, sanctions expansions, or trade restrictions could disrupt production and earnings visibility.
Supply-chain concentration also creates vulnerability to shocks, whether from geopolitical escalation, cyber interference, or logistical disruption. Markets may underestimate how quickly these risks can materialise and cascade across sectors.
Escalation risk remains an overarching concern. Any broadening of the conflict or spillover into other regions could trigger sharp market volatility, particularly across defence, energy, and emerging markets. ESG considerations further complicate defence exposure for some investors, requiring careful alignment between fiduciary duty, mandate constraints, and reputational risk.
Strategic Outlook
The convergence of Chinese manufacturing, drone warfare, and geopolitical competition has created a complex and evolving landscape. Globalized supply chains that once drove consumer electronics efficiency now create strategic dependencies that governments are actively addressing. Defense, technology, and industrial supply chains are increasingly interconnected with broader geopolitical and commercial networks, shaping both operational and market outcomes.
Defense exposure reflects more than a hedge against geopolitical risk. It also captures structural shifts in how militaries operate and adopt technology. Efforts to regionalize supply chains, particularly in semiconductors, batteries, and critical components, are reshaping global manufacturing patterns. Companies producing dual-use technologies in China carry risks that are not always visible, requiring careful monitoring and selective positioning.
The global supply chain of war is not only influencing the Russia–Ukraine conflict but also redefining the architecture of manufacturing, technology development, and strategic competition worldwide. Understanding these dynamics and integrating them into strategy will be essential to navigate the evolving geopolitical and economic landscape over the coming decade.
Subscribe to our newsletter
Disclaimer: This article does not constitute financial advice nor a recommendation to invest in the securities listed. The information presented is intended to be of a factual nature only. Past performance is not a reliable indicator of future performance. As always, do your own research and consider seeking financial, legal and taxation advice before investing.
Speak to an Advisor
Inside Anthropic’s IPO filing: explore its soaring revenue, computing commitments, reported losses and governance structure, and what the disclosures mean for investors.
Big Tech reports next week. Learn how to read earnings releases and filings, and what to look for in AI spending, cloud growth, cash flow and guidance.
Understand how AI investment could affect global financial stability, as the IMF and RBA warn of rising debt, market concentration and funding risks.
Firmus’ proposed mega-IPO puts a spotlight on the cost, capital intensity and risks of building AI infrastructure as investors weigh the next phase of the AI boom.
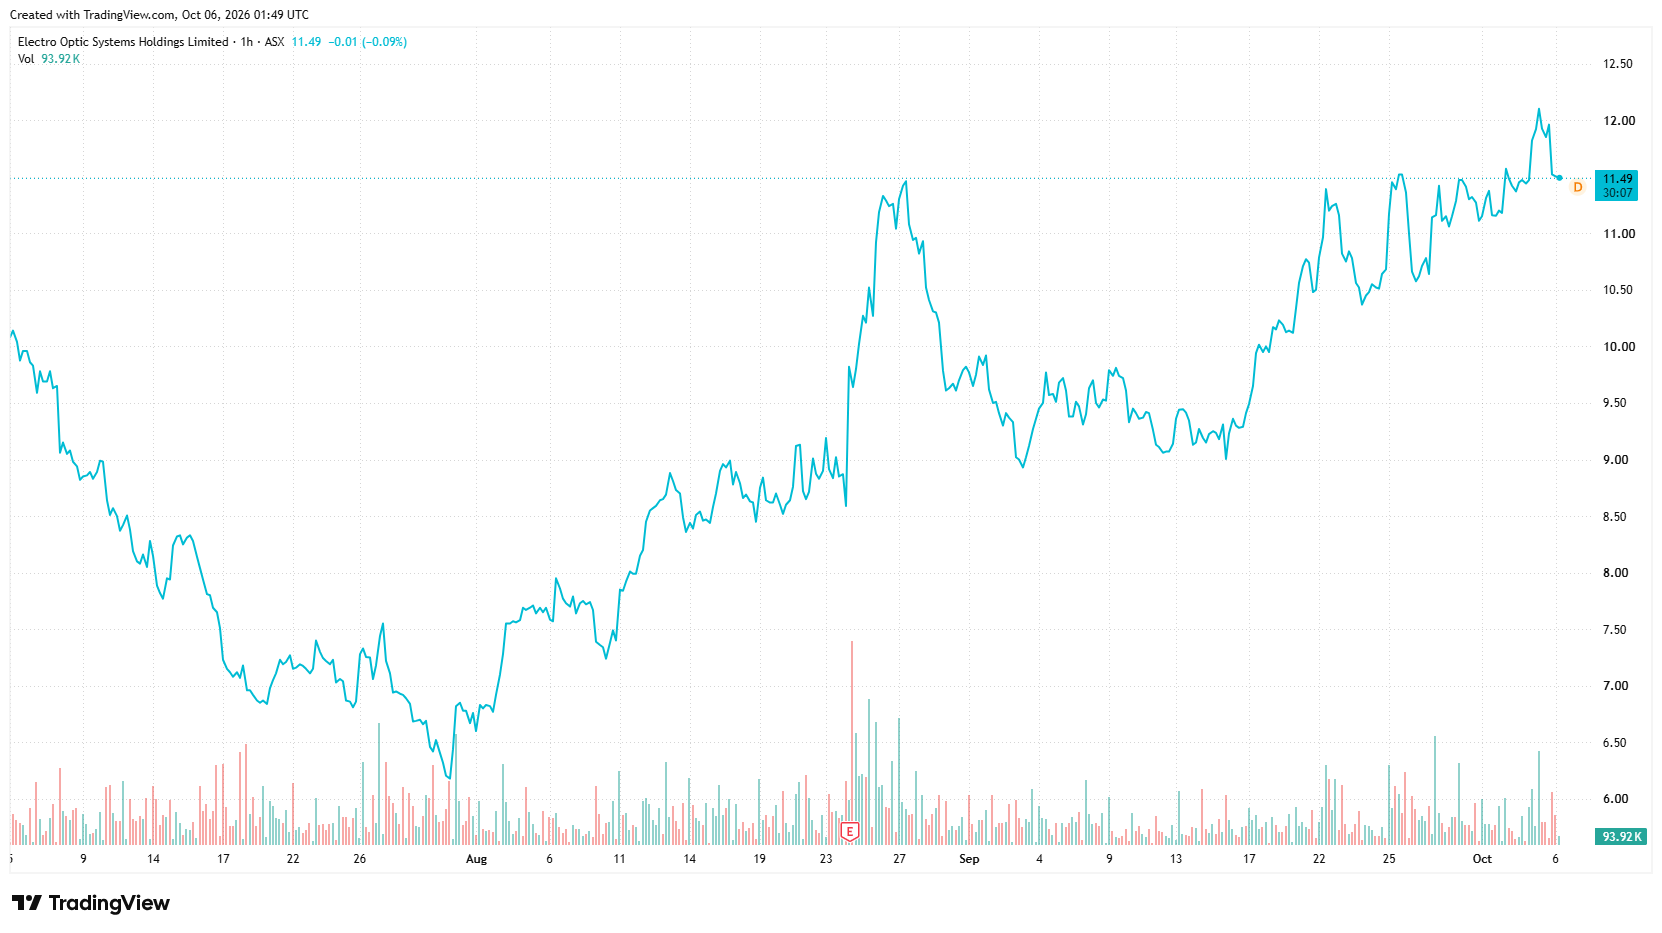
About Electro Optic Systems Holdings Ltd. Electro Optic Systems Holdings Limited engages in the development, manufacture, and sale of telescopes and dome enclosures, laser satellite tracking systems, remote weapon systems, and high laser weapon. It operates through Defense Systems and Space Systems segments. The company develops, manufactures, and markets fire control, surveillance, weapon systems, and high energy laser to military customers. It also provides passive optical and laser sensing equipment; optical, microwave and on-the-move radio and satellite products; and laser-based surveillance systems with space tracking capability. In addition, the company offers counter-drone, firepower, force protection, and UGV and marine lethality systems, as well as high energy laser weapon; optical tracking systems, space control, space domain awareness, satellite laser ranging, space sustainability, and precision optics. It operates in Australia, the United States, Singapore, the United Arab Emirates, the United Kingdom, New Zealand, the Netherlands, North America, Germany, and rest of Europe. Electro Optic Systems Holdings Limited was founded in 1983 and is based in Symonston, Australia. Source: EODHD Key Stats
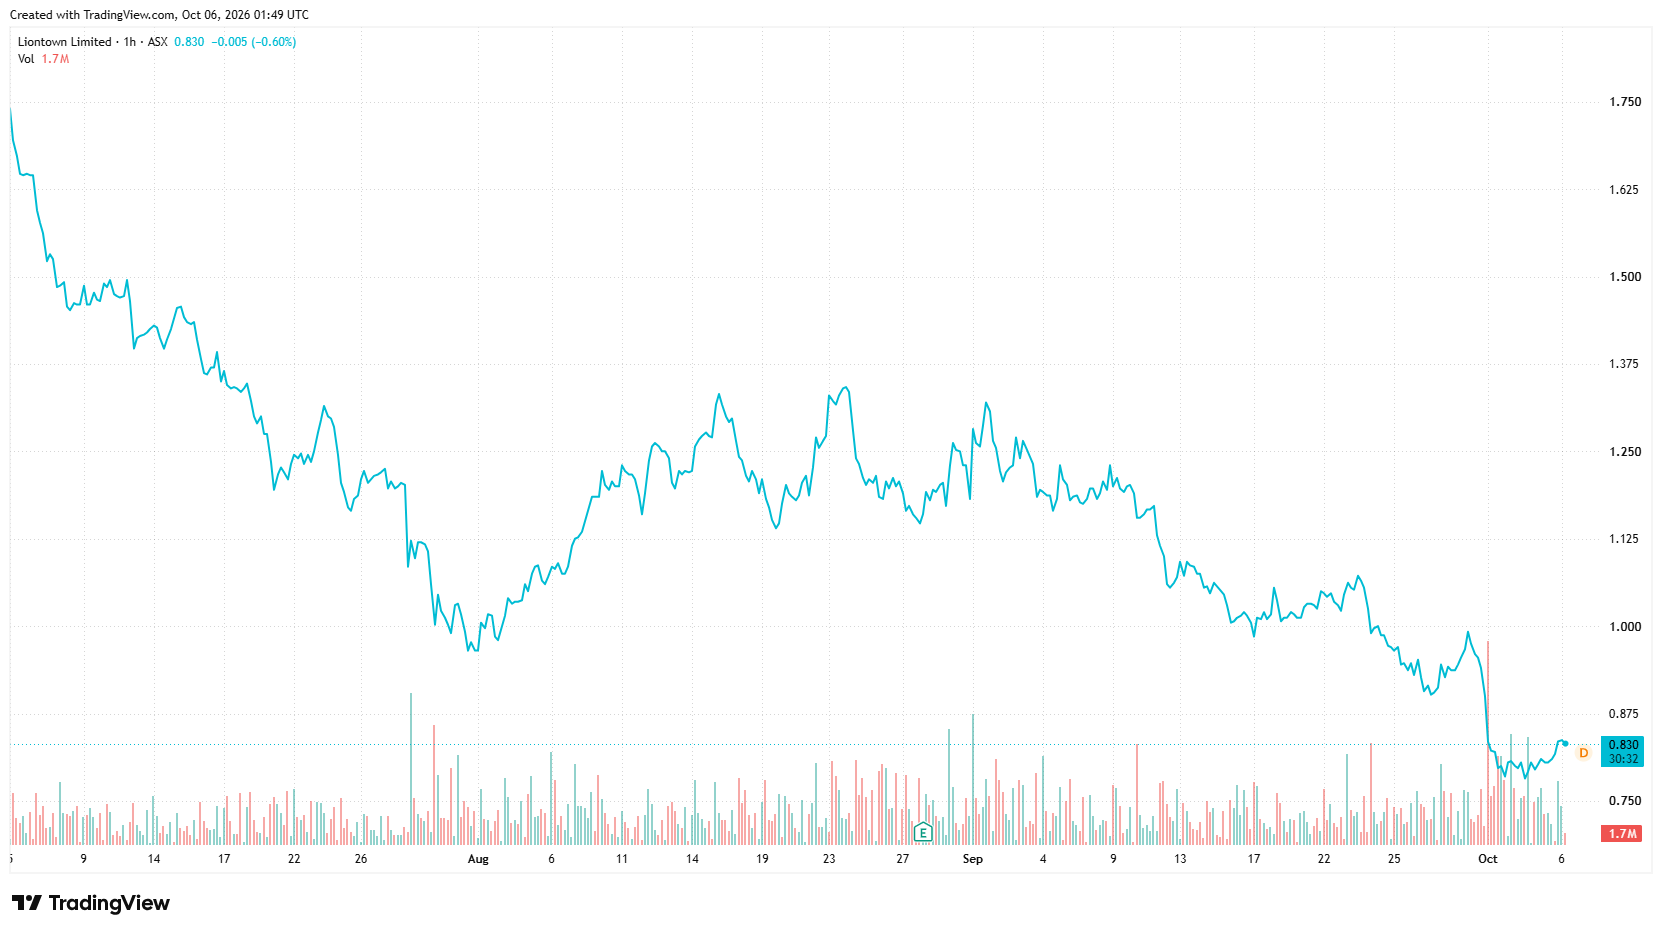
About Liontown Ltd. Liontown Limited engages in the exploration, evaluation, and development of mineral properties in Australia. It primarily explores for lithium, gold, and nickel deposits. The company's flagship property is the Kathleen Valley lithium project located in Perth, Western Australia. The company was formerly known as Liontown Resources Limited and change its name to Liontown Limited in November 2025. Liontown Limited was incorporated in 2006 and is headquartered in West Perth, Australia. Source: EODHD Key Stats
The RBA has raised rates to 4.60% as inflation pressures persist. Explore the impact of energy costs, AI demand and the key signals investors should watch next.
Discover how advances in genomics, AI, diagnostics and gene editing are creating a broader healthcare opportunity and where commercial value is emerging.
The AI trade is being forced to rethink the pace of progress. Here is what investors should watch across Nvidia, chips, AI spending, software and adoption.

Copper is at a record high, yet the global market still has a surplus. So where is all the copper, and why is it becoming harder to find?
