From Property to Portfolios: How the 2026 Budget Could Reshape Australian Investing
A Watershed Budget for Australian Investors
The 2026 Federal Budget delivered what may prove to be the most significant shift to Australian investment taxation in more than two decades. Two reforms sit at the centre of the changes: negative gearing for residential property will be limited to new builds, while the long-standing 50% capital gains tax discount will be replaced by a system based on cost-base indexation alongside a new 30% minimum tax rate on capital gains.
Public discussion to date has focused largely on housing affordability and the political implications for the property market, which is understandable given the central role housing plays in Australia’s economy and household wealth. Yet the more significant long-term story for investors may sit beyond housing itself. These reforms have the potential to reshape capital allocation, portfolio construction and investor behaviour across the country by challenging a framework that has structurally incentivised residential property investment for more than two decades.
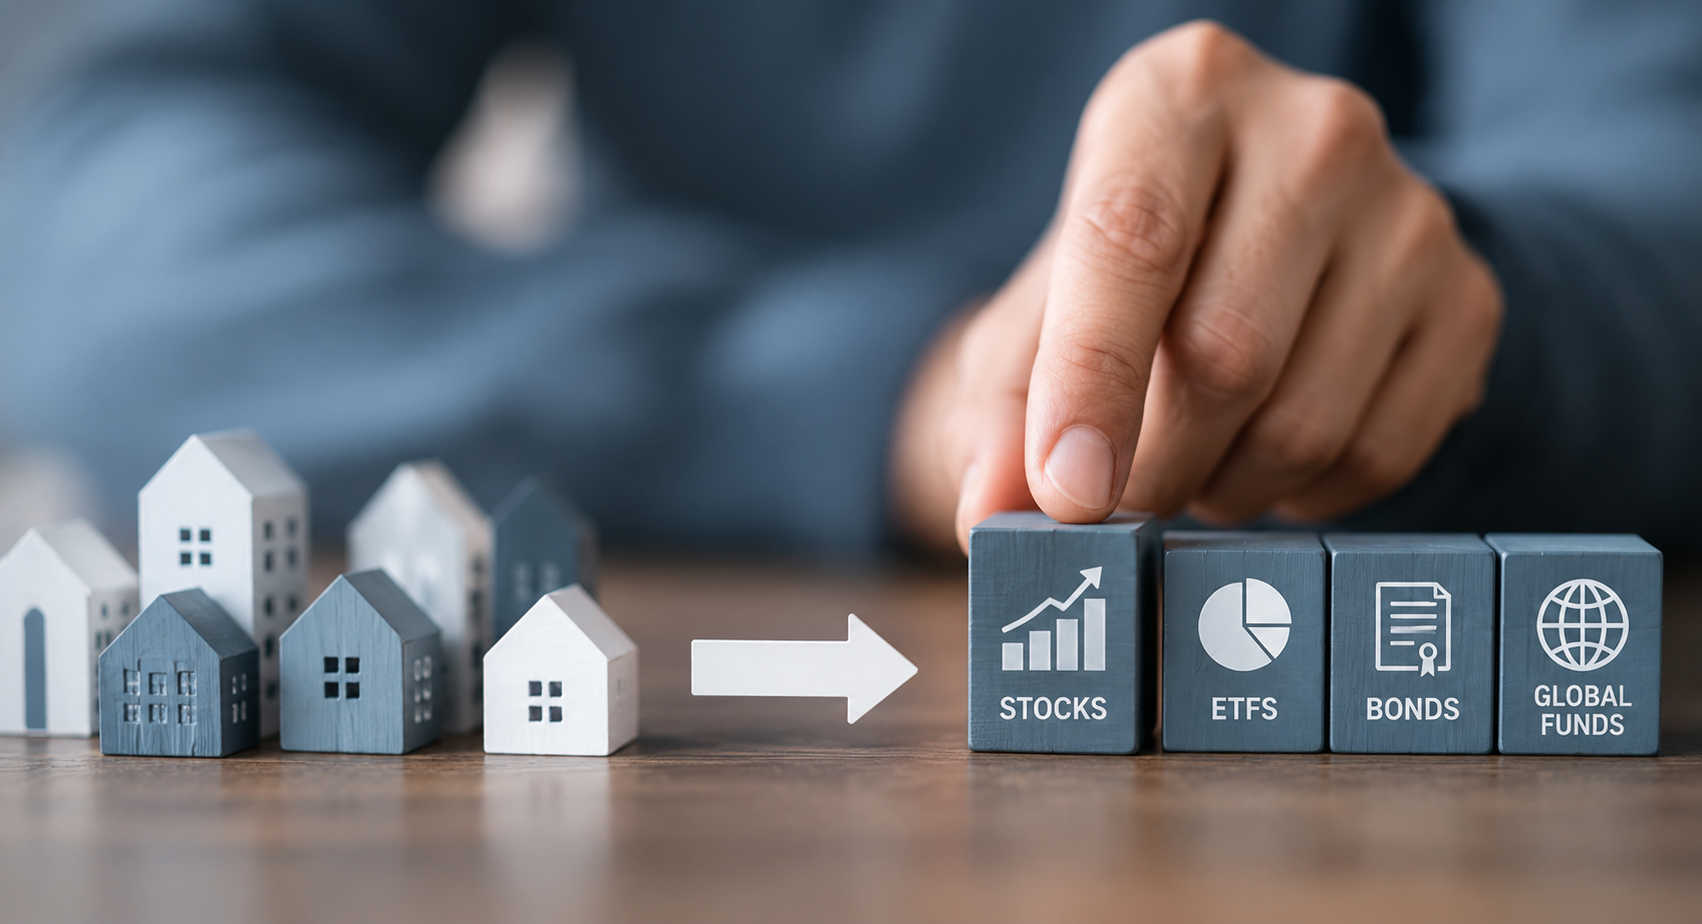
This does not signal the end of property investing. Residential property will likely remain a core component of Australian household wealth for years to come. However, the Budget may accelerate a broader transition already underway: the shift from highly concentrated property exposure towards more diversified, portfolio-based investing.
That raises a larger question for investors. If the tax environment underpinning Australia’s traditional wealth-building model is beginning to change, where does capital flow next?
Australia’s Longstanding Reliance on Property
Australia has long been one of the most property-centric investment markets in the developed world. Residential housing is estimated to account for roughly 55% of total household assets, placing Australia among the most housing-concentrated economies in the OECD. For generations, property ownership has been viewed not simply as a lifestyle aspiration, but as the foundation of long-term financial security.
Several structural forces helped create this environment. Negative gearing encouraged leveraged property investment by allowing investors to offset losses against taxable income, while the introduction of the 50% CGT discount in 1999 materially improved after-tax investment returns. Australia also experienced a prolonged period of declining interest rates, strong population growth and persistent housing supply constraints, all of which supported rising property prices.
Cultural factors reinforced the trend. The “great Australian dream” extended beyond home ownership into investment property accumulation, with many households viewing real estate as a safer and more tangible wealth-building vehicle than equities or financial markets. Property also became deeply intertwined with retirement planning and intergenerational wealth transfer strategies.
The result has been a national investment culture heavily concentrated in a single asset class, often without investors fully recognising it as concentration risk. When a strategy has worked for an entire generation, it gradually stops feeling like a bet. Many Australian households effectively built their wealth around a familiar structure consisting of the family home, one or two investment properties, superannuation and a relatively modest allocation to equities.
That model delivered strong results during an era of falling interest rates, favourable taxation settings and rising property values. The question now is whether the conditions supporting that strategy are beginning to evolve.
Why the 2026 Budget Matters Beyond Housing
The significance of the 2026 Budget lies not only in the reforms themselves, but in what they signal about the future direction of Australian investment policy.
Under the new framework, the 50% CGT discount will be replaced from 1 July 2027 with a cost-base indexation regime alongside a new 30% minimum tax rate on capital gains. Negative gearing for residential property will also be limited to new builds, with losses on established properties acquired after Budget night effectively quarantined. Existing holdings retain grandfathering protections, while gains accrued prior to July 2027 preserve current treatment. Meanwhile, superannuation retains its one-third CGT discount, a detail that may materially influence future capital allocation decisions.
At one level, the reforms are designed to improve housing affordability and increase housing supply. At a deeper level, they reflect a growing willingness by government to influence how investment capital is distributed across the economy.
For more than 25 years, Australia’s tax settings structurally favoured leveraged investment into established residential property. The combination of negative gearing and concessional CGT treatment created a powerful after-tax incentive that shaped investor behaviour across multiple generations.
The Budget does not eliminate property investment incentives altogether. The preservation of incentives for new developments appears specifically designed to redirect capital towards increasing housing supply rather than speculative accumulation of existing dwellings. However, it materially reduces the after-tax attractiveness of one of Australia’s most common wealth-building strategies: purchasing established investment properties for capital appreciation.
That distinction matters because the implications extend beyond housing. The CGT changes apply across all CGT assets, including equities, ETFs, business interests and other investment structures. Investors are now being pushed to think more carefully about after-tax returns, diversification and portfolio efficiency across multiple asset classes.
In that sense, the reforms may reshape not only housing behaviour, but the broader psychology of Australian investing itself.
Investors May Be Starting to Diversify
The rotation away from established residential property is not merely theoretical. Early signs of changing investor behaviour are already emerging, even before the 1 July 2027 commencement date.
Several housing indicators have softened since the Budget announcement. Commonwealth Bank economists now forecast house prices to settle around 3% lower than they otherwise would have, directly attributing part of the adjustment to the proposed reforms. ANZ expects Sydney dwelling prices to decline by approximately 0.7% and Melbourne by 1.7% during 2026, with weakness already becoming visible across the upper quartile of both markets.
At the same time, capital is increasingly flowing into alternative investment channels. ETFs continue attracting record inflows, reflecting growing demand for diversification, liquidity and easier access to both domestic and international markets. ASX-listed gold ETFs alone attracted approximately AUD1.6 billion in inflows during 2025.
Investor participation is also expanding across:
- ETFs and managed funds
- Direct Australian equities
- International equities through both ASX-listed global ETFs and direct offshore share trading
- Passive and index-based investment strategies
Younger investors are also approaching wealth creation differently from previous generations. Compared with earlier cohorts, they are generally more comfortable with digital investment platforms, global markets and portfolio-based investing. International equities, ETFs and diversified investment strategies are increasingly viewed as normal components of long-term wealth creation rather than specialist or institutional products.
This does not imply the end of Australia’s property culture. Residential property will likely remain a significant component of household wealth for years to come. However, portfolio-based investing is gradually becoming more mainstream in Australia, and the 2026 Budget may accelerate a transition that was already beginning to emerge.
Where Capital Could Flow Next
If billions of dollars of capital are gradually redirected away from established residential property, the natural question becomes where that money flows next.
Australian equities remain the most obvious destination, particularly income-oriented sectors such as banks, infrastructure, utilities and other dividend-paying businesses. As the gap between the tax treatment of dividends and capital gains narrows, franked income may become relatively more attractive for domestic investors seeking both yield and liquidity.
Global equities may attract an increasing share of redirected capital. The ASX remains heavily concentrated in financials and resources, while many of the world’s largest structural growth sectors including artificial intelligence, semiconductors, cloud computing, cybersecurity and advanced healthcare remain dominated by international markets, particularly the United States.
Superannuation and SMSF strategies may also become structurally more attractive under the preserved concessional tax treatment and retained one-third CGT discount. That could drive renewed interest in concessional contributions, salary sacrifice arrangements and longer-term tax-efficient investment strategies through superannuation vehicles.
ETFs and managed funds are also likely beneficiaries given their diversification, accessibility, liquidity and relatively efficient tax structures. For investors shifting from concentrated property exposure towards broader portfolio construction, exchange-traded funds offer one of the simplest pathways into diversified investing across multiple sectors and geographies.
Alternative assets including infrastructure, private credit and agricultural investments may similarly attract greater attention from investors seeking defensive income streams and portfolio diversification outside traditional residential property exposure.
This is unlikely to become a wholesale exit from property investing. Incentives for new developments remain intact, meaning some capital may stay within the sector but rotate towards areas aligned with government policy objectives. The reforms appear designed less to eliminate property investment and more to broaden how Australians allocate capital across their portfolios.
What a Modern Australian Portfolio May Look Like
For decades, the traditional Australian wealth blueprint looked broadly the same: the family home, one or two investment properties, exposure to the major banks, cash reserves and superannuation. That structure was built for a tax and interest rate environment that may now be changing.
As a result, investors may increasingly begin thinking about portfolio construction through a broader lens. The 2026 Budget is a reminder that concentration risk matters, particularly when household wealth is heavily tied to a single asset class and the policy settings supporting it.
Modern portfolio construction increasingly focuses on:
- Diversification across asset classes, not simply within them
- Total return thinking that combines income, capital growth and reinvestment rather than focusing solely on yield
- Geographic exposure that reflects the increasingly global nature of the modern economy
- Sector balance to reduce over-reliance on financials, property and resources
- Liquidity and flexibility, which become increasingly valuable during market dislocations and retirement planning
Institutional investors have long approached investing this way, allocating across domestic and international equities, fixed income, infrastructure and alternative assets rather than concentrating heavily in one market or sector.
That does not mean residential property loses relevance. Rather, it may become one component within a broader and more diversified portfolio framework rather than the defining centrepiece of wealth creation. Increasingly, the conversation is no longer “property versus shares”, but how Australians construct resilient portfolios across multiple asset classes and global markets.
A Strategic Inflection Point for Australian Investors
The 2026 Budget may ultimately prove significant not because it changed property taxation, but because it altered the strategic questions Australian investors now need to ask.
Property will likely remain a core part of Australian household wealth for decades to come. Existing holdings retain important grandfathering protections, and Australia’s long-term housing fundamentals remain supported by population growth and structural supply constraints.
However, the environment for deploying new capital may now be changing.
The reforms may accelerate trends already emerging across Australian investing: greater diversification, increased use of ETFs and managed funds, rising participation in global markets and a broader focus on portfolio construction rather than single-asset concentration.
Australian investing may be entering a new phase, one where wealth creation becomes less concentrated around residential property and increasingly built around diversified, globally connected portfolios.
And if Australian investors are beginning to think beyond property, the next question may be whether they should also begin thinking beyond the ASX.
Subscribe to our newsletter
Disclaimer: This article does not constitute financial advice nor a recommendation to invest in the securities listed. The information presented is intended to be of a factual nature only. Past performance is not a reliable indicator of future performance. As always, do your own research and consider seeking financial, legal and taxation advice before investing.
Speak to an Advisor