Stock Spotlight: Costco Wholesale Corp (NASDAQ:COST)
About Costco Wholesale Corp
Costco Wholesale Corporation, together with its subsidiaries, engages in the operation of membership warehouses in the United States, Puerto Rico, Canada, Mexico, Japan, the United Kingdom, Korea, Australia, Taiwan, China, Spain, France, Iceland, New Zealand, and Sweden. It offers merchandise, including sundries, dry groceries, candies, coolers, freezers, deli, liquor, and tobacco; non-food merchandise comprising appliances, small electronics, health and beauty aids, hardware, lawn and garden, sporting goods, tires, toys and seasonal, automotive, stamps, tickets, apparel, furniture, domestics, housewares, special order kiosks, and jewelry; and fresh food, such as meat, produce, service deli, and bakery products. The company is also involved in warehouse ancillary operations, which include gasoline, pharmacies, optical, food courts, hearing-aid centers, and tire installation centers. In addition, it engages in e-commerce, business centers, travel, and other businesses. The company was formerly known as Costco Companies, Inc. and changed its name to Costco Wholesale Corporation in August 1999. Costco Wholesale Corporation was founded in 1976 and is based in Issaquah, Washington.
Source: EODHD
Key Stats
Key Stats
Source: EODHD. Data as of 10/06/26.
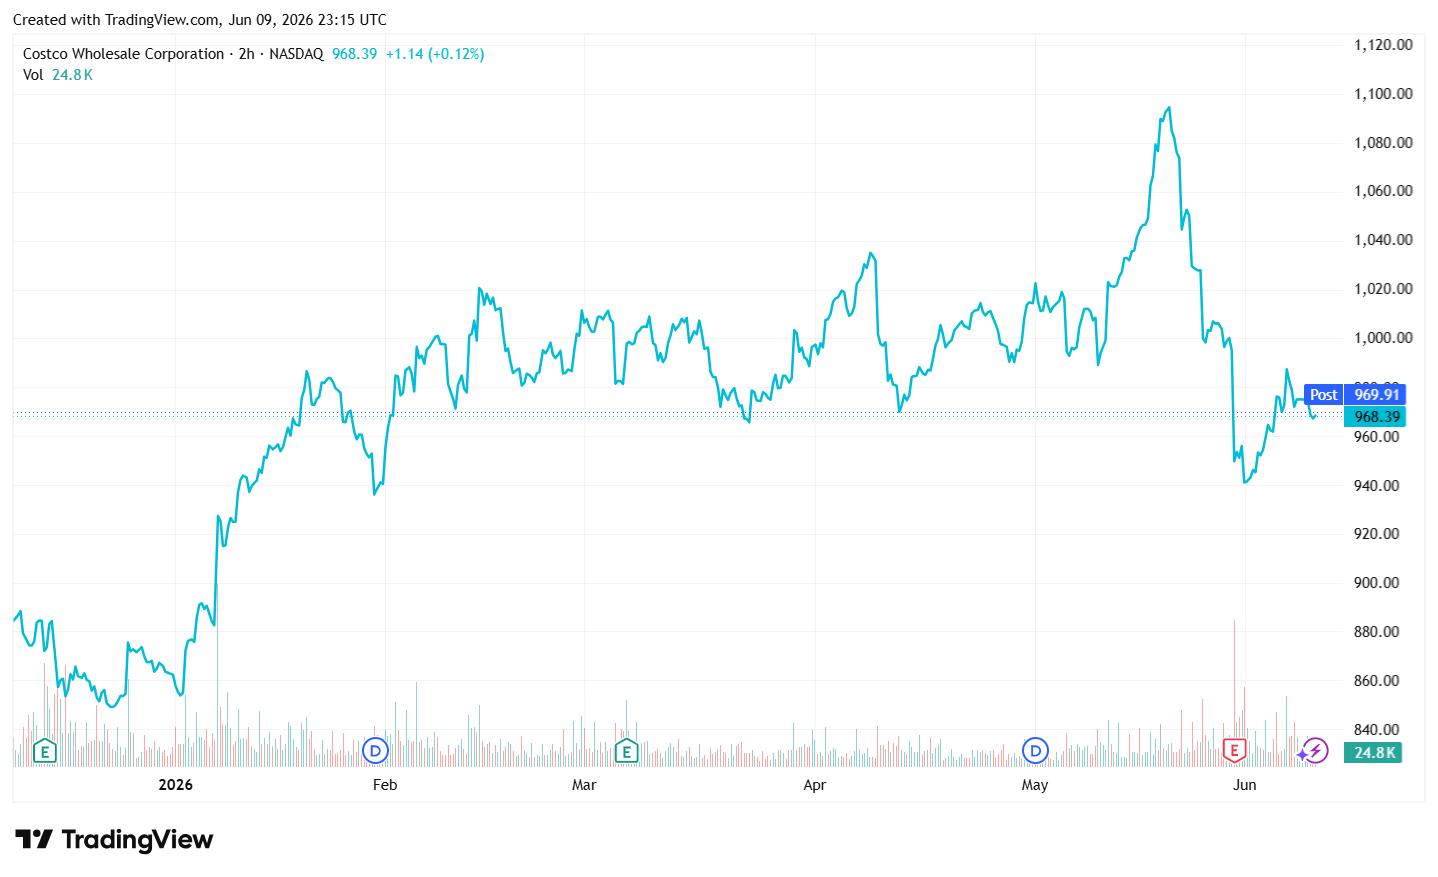
Price Performance
Growth Potential
- Strong and differentiated business model with membership-fee structure providing a recurring revenue component (membership fees account for ~2% of revenue but ~70-80% of operating income) and warehouse club model (limited SKUs allows to focus on high-turn, high value items and negotiate with suppliers) helping maintain operational simplicity, giving it steadier cash flows and less dependence solely on merchandise margin expansion. COST leverages its scale and passes cost savings onto members (vs maximizing margins), which builds loyalty (membership renewal rates are exceptionally high - ~93% U.S./Canada and ~90% worldwide).
- Scale-driven cost leadership and pricing power with limited SKU count (~4000 vs 100,000 for typical retailers) and high turnover rate enabling unmatched purchasing power and supply-chain efficiency.
- Durability across economic cycles with COST performing well in recessions (because of its perceived value proposition of “premium goods at warehouse prices”) and inflationary environments (fixed markup model means customers trust company to protect them from price gouging, increasing traffic and renewal rates).
- Consistent growth with same-store sales (ex-fuel and ex-FX) having grown mid-to-high single digits annually for much of the last decade while e-commerce, although a smaller mix, is growing double-digits. Operating leverage is achieved by scaling membership fees and improving procurement efficiency.
- High quality – high ROIC (consistently >20%), net cash, and disciplined capital allocation (organic growth, modest buybacks and member-focused investments).
- COST can increase membership fees, which should drop directly to the bottom line. COST has not raised prices since 2017 - historically it raises prices every 5-6 yrs.
Key Risks
- Low margin business / Macroeconomic headwinds (inflation, recession).
- Store saturation and maturity risk (incremental growth from square footage may taper and same-store sales growth can flatten).
- Supply chain risks especially with new international operations.
Subscribe to our newsletter
Disclaimer: This article does not constitute financial advice nor a recommendation to invest in the securities listed. The information presented is intended to be of a factual nature only. Past performance is not a reliable indicator of future performance. As always, do your own research and consider seeking financial, legal and taxation advice before investing.
Speak to an Advisor