Stock Spotlight: Uber Technologies Inc (NYSE:UBER)
About Uber Technologies Inc
Uber Technologies, Inc. develops and operates proprietary technology applications in the United States, Canada, Latin America, Europe, the Middle East, Africa, and the Asia Pacific. It operates through three segments: Mobility, Delivery, and Freight. The Mobility segment connects consumers with a range of transportation modalities, such as ridesharing, carsharing, micromobility, rentals, public transit, taxis, and other modalities; and offers riders in a variety of vehicle types, as well as financial partnerships products and advertising services. The Delivery segment allows consumers to search for and discover restaurants to grocery, alcohol, convenience, and other retails, as well as order a meal or other items, and either pick-up at the restaurant or have it delivered; and provides Uber direct, a white-label delivery-as-a-service for retailers and restaurants, as well as advertising services. The Freight segment manages transportation and logistics network, which connects shippers and carriers in digital marketplace, including carriers upfronts, pricing, and shipment booking; and offers on-demand platform to automate logistics end-to-end transactions for small-and medium-sized business to global enterprises. The company was formerly known as Ubercab, Inc. and changed its name to Uber Technologies, Inc. in February 2011. Uber Technologies, Inc. was founded in 2009 and is headquartered in San Francisco, California.
Key Stats
Key Stats
Source: Yahoo Finance. Data as of 11/09/25.
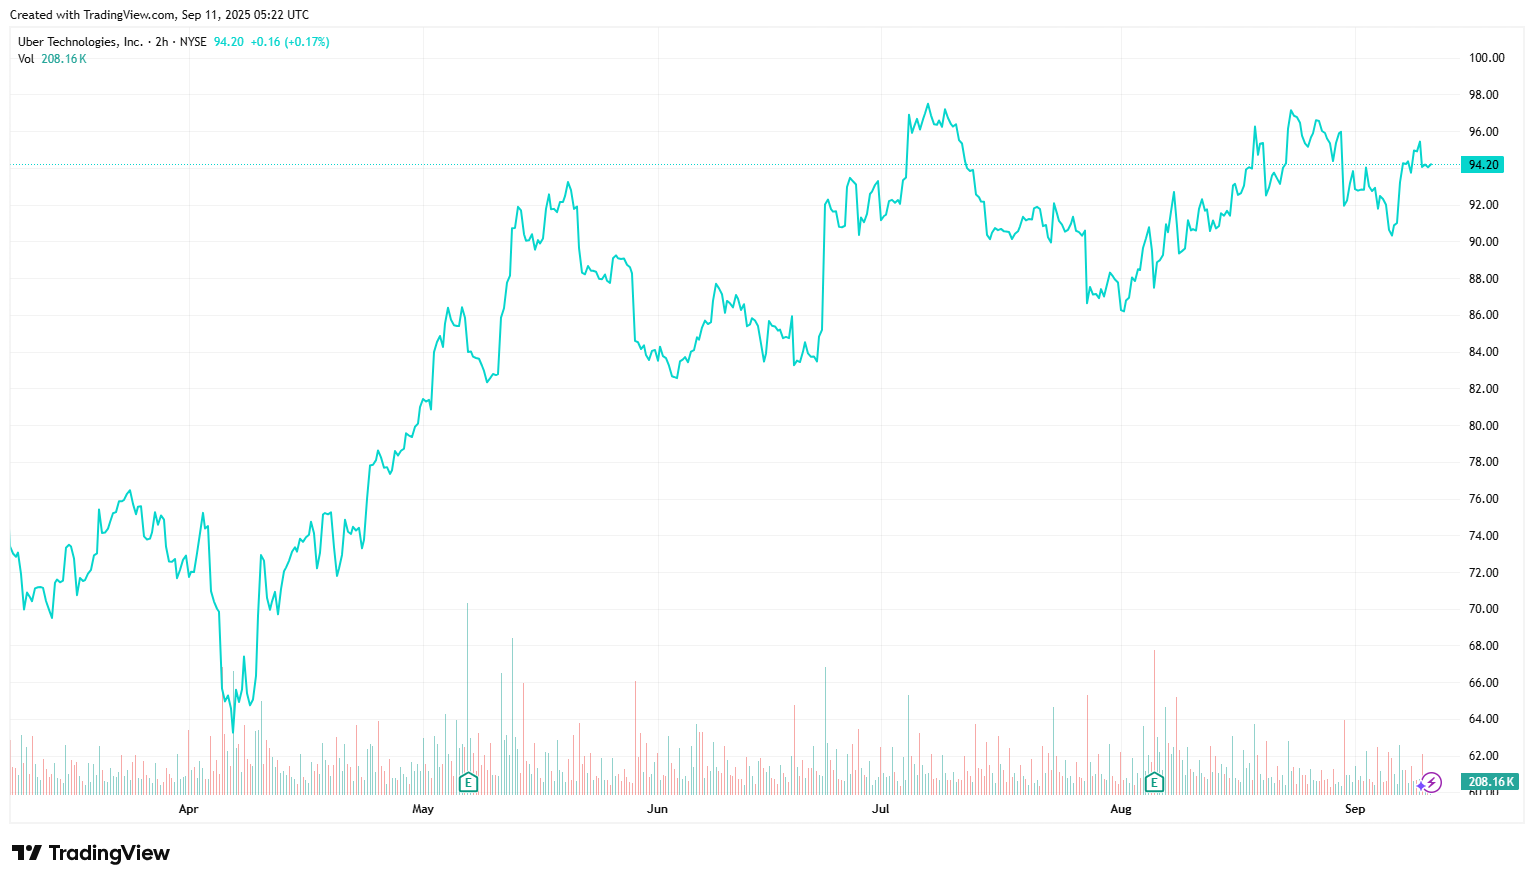
Price Performance
Growth Potential
- Global leader in ridesharing and food delivery, who we believe is set to benefit from significant scale as the company continues to focus on improving profitability.
- Platform synergies (strategically investing in new use cases beyond food delivery, such as grocery and retail which has led to sharp increases in consumer metrics, including retention) with the company benefiting from cross-platform user engagement (higher utilization rates > higher earnings potential for drivers > lower need to incentivize supply > lower prices for consumers > more demand from consumers/merchants).
- Improving margin profile (scaling revenue while keeping SG&A and R&D disciplined) which combined with management’s focus on minimizing investments should translate to higher potential shareholder returns.
- AV partnerships should be a tailwind and increase utility rate (given humans can drive only 6-8 hours/day which leads to demand exceeding the supply in rush hours and dropping drastically at other times providing limited benefit to the company from rising prices in rush hours because of supply constraints while being hit from lower prices in dead hours).
- Capital management - UBER plans to allocate ~50% of FCF to buybacks.
Key Risks
- Increasing competition impacting volumes and pricing.
- Regulatory/legal risks including government regulations
- High dependence on gig-economy workforce with any shortages of drivers/supply due to factors like lower wages or better job opportunities elsewhere, could lead to the company facing issues with fulfilling ride demand.
- Sensitivity to economic downturns with a potential recession/economic slowdown leading to lower demand for premium services (Uber Reserve) and impact to gross bookings.
Subscribe to our newsletter
Disclaimer: This article does not constitute financial advice nor a recommendation to invest in the securities listed. The information presented is intended to be of a factual nature only. Past performance is not a reliable indicator of future performance. As always, do your own research and consider seeking financial, legal and taxation advice before investing.
Speak to an Advisor